
Car Insurance in Fremont, CA
Not every Fremont driver puts the same miles in. Maybe you work from home, or maybe the 680 is somewhere you rarely find yourself. Either way, you shouldn’t pay a flat rate for miles you never drove.
Lemonade Pay Per Mile makes sure you don’t.
How much does car insurance
cost in Fremont?
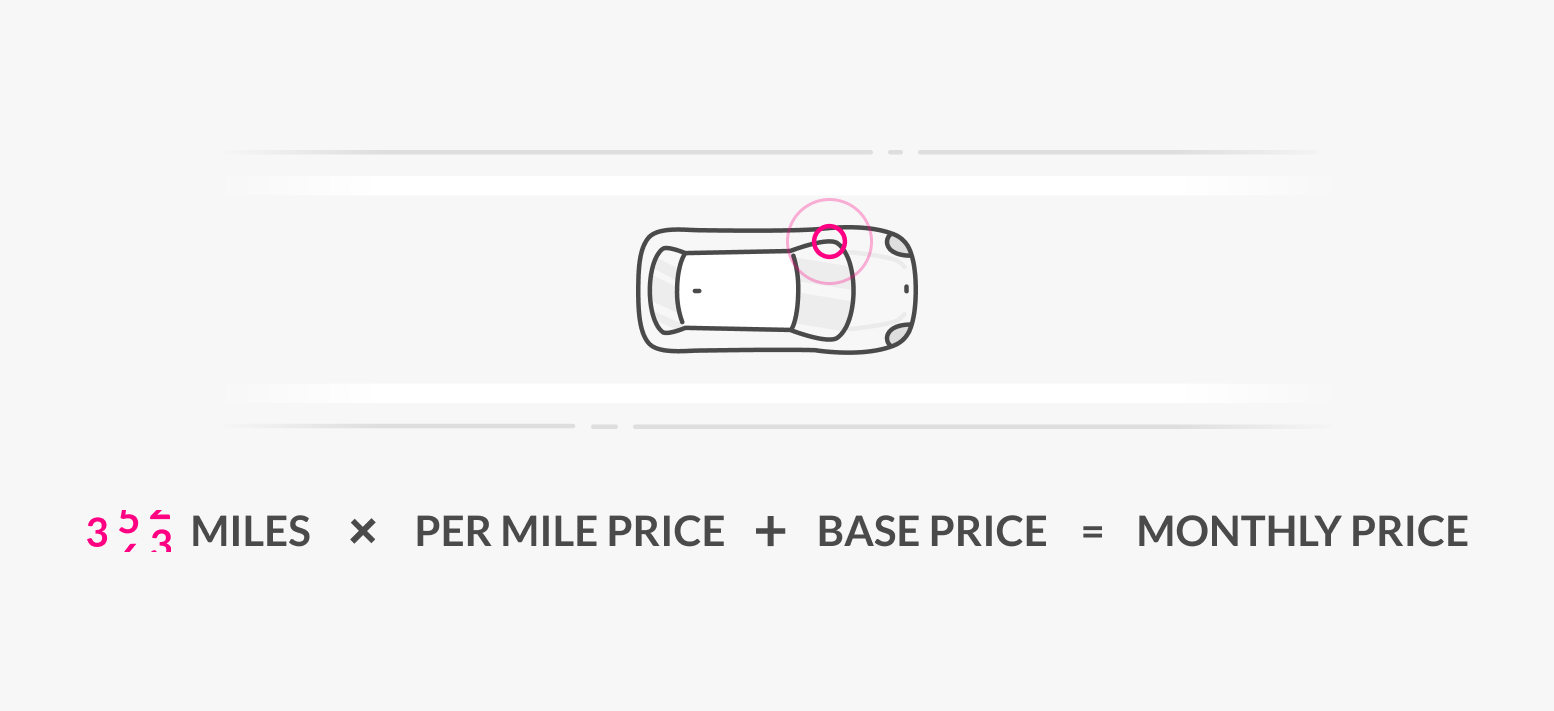
The average estimated cost of Lemonade car insurance in Fremont ranges from roughly $2,400 to $2,460 per year*. You’ll pay a different price each month; it’s a calculation of the number of miles you drive multiplied by your per-mile price, plus your monthly base price that doesn’t change.
How can I get cheaper car insurance in Fremont?
The savings don’t stop at signup. Here’s what else is on the table.
Bundle discounts
The more you bundle with Lemonade, the more you save. Car, renters, homeowners, pet, and more.
Safe driving
The safer you drive, the lower your premium. We look at things like speed, braking, and how smoothly you take turns.
Low mileage
The less you drive, the less you pay. Every month, no exceptions.
What is the minimum car insurance
required in Fremont?
Every Fremont driver needs to carry a minimum level of coverage to legally drive. Here’s exactly what California requires.
| Required minimum coverages for Tennessee drivers | Minimum amount required |
|---|---|
| Bodily injury liability | $30,000(per person)/ $60,000 (per accident) |
| Property damage liability | $15,000 |
What additional car insurance coverages
does Lemonade offer in Fremont?
The state minimum covers the basics. These coverages help fill in the gaps.
Collision coverage
To repair or replace your own car if it’s damaged in an accident with another vehicle, or a stationary object (like a fence, highway divider, and so on).
Read moreComprehensive coverage
To fix damage to your car, or possibly replace it entirely, if there are damages or losses from an incident that didn’t involve a collision with another vehicle (like if you hit a deer, damage from a hailstorm, and so on).
Read moreMedical payments coverage (aka MedPay)
Medical expenses for you or a passenger in your car after a crash- like ambulance fees, hospital visits, and health insurance co-pays, or for funeral services (in a worst case scenario). Usually doesn’t have a deductible.
Read moreUninsured / underinsured motorist bodily injury coverage
Can help cover your medical bills and lost wages related to injuries caused by an uninsured or underinsured driver.
Read moreUninsured motorist property damage coverage
Can help repair or replace your own car if you get into a car accident with an uninsured or underinsured driver.
Read moreTemporary transportation coverage
Transportation expenses like rideshares, public transportation, bike sharing, or a rental car for up to 30 days while your car is being repaired or appraised.
Read moreWhat’s the best car insurance in Fremont?
Better pricing. Faster claims. Perks that actually matter.
Here’s what you get when your insurer is built on tech, not paperwork.
Priced for you
Most insurers average you in with everyone else. We don’t. Your price is built around how you drive. Not the driver next to you.
No hold music
Buy a policy, add a car, file a claim, update your coverage. All from the app, all in minutes.
Claims, not chaos
Open the app, tell us what’s going on, and we’ll take it from there. Fast, clear, and no runaround.
What are Fremont drivers driving?
Next time you’re stuck on 680 through the Sunol Grade toward San Jose, play along.
Here are the nine makes you’re most likely to spot on Fremont roads, according to our data.
Fremont drivers, by the numbers
Fremont roads have a story to tell. Here’s what our data found.
Beyond Fremont: car insurance across California
Fremont car insurance FAQs
What happens if you drive without insurance in Fremont?
California law requires all drivers to carry at least the state minimum liability coverage, and getting caught without it in Fremont can mean fines, a suspended license, and even vehicle impoundment. If you cause an accident while uninsured, you’re personally on the hook for the other driver’s injuries and property damage. It’s a risk that’s not worth taking.
How does Fremont's weather affect my car insurance?
Fremont sits in the Bay Area, where summer wildfire smoke, occasional heavy rain, and dense fog on the Dumbarton Bridge corridor can all make driving trickier than usual. Comprehensive coverage can help protect your car from smoke and ash damage, while collision coverage steps in if slick roads lead to an accident. Knowing what your policy covers before conditions get rough is always a smart move.
Is car insurance more expensive for younger drivers in Fremont?
Younger drivers typically pay more for car insurance, but safe habits behind the wheel can bring that cost down more than most people expect. Pay-per-mile insurance is especially worth a look for young Fremont drivers who commute by BART or bike on lighter days, since lower mileage can translate directly to lower costs.
What coverage options go beyond California's state minimum?
California’s minimum only covers damage and injuries you cause to others, leaving your own car unprotected. Adding collision coverage helps pay for repairs to your car after an accident, while comprehensive coverage handles things like theft, vandalism, fire, and weather-related damage. Given Fremont’s proximity to high-traffic highways like I-880 and I-680, a little extra coverage can go a long way.
What should I do after a car accident in Fremont?
First, make sure everyone is safe and call 911 if there are any injuries. Then exchange insurance and contact information with the other driver, document the scene with photos, and report the accident to your insurance company as soon as possible. If the accident happens on a busy stretch like the I-880 corridor, move to a safe location off the roadway before doing anything else.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage and discounts may not be available in all states. Lemonade Insurance analyzed policy rates to calculate average car premiums from Oct 2025 through September 2026. This analysis is based on Lemonade’s internal data and is meant for illustrative purposes only; quotes may vary depending on individual circumstances. Vehicle make rankings reflect active Lemonade Car policyholders in California as of September 2026, based on Lemonade’s internal data. Claims statistics reflect Lemonade Car claims filed in California between October 2025 and September 2026; all figures are based on Lemonade’s internal claims data, intended for illustrative purposes only, and may not be representative of all California drivers or the broader insurance market.
Continue Reading
How Much Does Car Insurance Cost in 2026?
Let’s dig into the factors that impact car insurance rates.
Pay Per Mile Car Insurance, Explained
Have stellar driving habits and spend less time behind the wheel than the average driver? Pay per mile car insurance could be a great fit.
Car Insurance for Electric Cars
We reward drivers for the environment-friendly driving choices they’re already making. Here are some of the perks.
Oxnard, CA Car Insurance
Get an auto insurance quote in Oxnard
Escondido, CA Car Insurance
Get an auto insurance quote in Escondido
Lancaster, CA Car Insurance
Get an auto insurance quote in Lancaster