
What Does Renters Insurance Cover in 2026
Renters insurance may cover more than you think.
Renters insurance may cover more than you think.
Renters insurance (also called tenant insurance, apartment insurance, or an HO-4 policy) covers four things: your stuff, your living costs if you can’t stay home, your liability if you hurt someone or damage their property, and a guest’s medical bills if they get hurt at your place.
It pays when a named peril causes the loss, like a fire, theft, or burst pipe. A peril is just the cause of the damage.
It doesn’t cover the building itself, which is your landlord’s responsibility, or floods and earthquakes.
 TL;DR
Renters insurance covers your stuff against theft, fire, vandalism, windstorms, plus liability if someone gets hurt at your place
Renters insurance has four main coverage types: personal property, loss of use (additional living expenses), personal liability, and medical payments to others
Floods, earthquakes, car damage, roommate’s belongings, and pest damage aren’t covered by standard policies
Your policy has limits, including sublimits for theft of jewelry ($1,500) and cash ($200). Extra Coverage lets you schedule jewelry, bikes, cameras, fine art, and musical instruments for broader protection, including accidental damage and no deductible.
Your renters insurance policy covers your belongings against named perils, like theft or fire. It also helps with extra living costs if a covered loss forces you out. And it can help if you’re responsible for someone’s injury, or for damage to their property.
Why “named perils”? The National Association of Insurance Commissioners (NAIC), a group of state insurance regulators, explains that a policy is either named-perils, which lists the losses it covers, or all-risk, which lists what it excludes. Renters coverage for your belongings typically works the first way. If the cause isn’t on the list, there’s no coverage for it.
Here are common scenarios, and the reason behind each answer.
| Scenario | Covered by renters insurance? | Why |
|---|---|---|
| Theft | Yes | Theft is a named peril, at home or away.¹ |
| Fire | Yes | Fire is a named peril. |
| Vandalism | Yes | Vandalism is a named peril. |
| Water damage | Depends on the cause | Sudden accidents are covered. Flooding and slow leaks aren’t. |
| Hurricanes | Mostly, but not flooding | Wind and hail are covered. Rising water is flood.² |
| Windstorms | Yes | Windstorm is a named peril. |
| Floods | No | Flood is excluded. It needs its own flood insurance. |
| Earthquakes | No | Earthquake is excluded. You’d need separate earthquake coverage. |
| Property used for commercial purposes | No | Business use needs business insurance. |
| Appliance breakdown | No, unless you add Equipment Breakdown Coverage (EBC) | Wear and mechanical failure aren’t named perils. EBC is an add-on. |
| Your roommate’s stuff | No | Your policy covers you, not other adults you live with. |
| Damage to or theft of your car | No | That’s what car insurance is for. |
| Your pet damages your stuff or the unit | No | Pet damage isn’t a named peril. |
| Your pet injures someone | Usually yes (liability) | Liability coverage protects you when you’re responsible for someone’s injury. |
| Pests (mice, rats, ants, bed bugs) | No | Pest damage and removal are excluded. |
| Property damage to the building | No | Your landlord’s insurance covers the building. |
Sometimes. It depends on where the water came from.
Sudden and accidental water damage is usually covered. Flooding isn’t. Here’s why: a burst pipe is a named peril, but water that comes in from outside is flood, and that needs its own policy.
Here’s how it plays out:
If you’re in a flood zone, ask about separate flood insurance. In the US, it’s available through the National Flood Insurance Program (NFIP).
A typical renters insurance policy (also known as an HO-4 policy) has four main coverage categories: personal property, loss of use (also known as additional living expenses), personal liability, and medical payments to others.
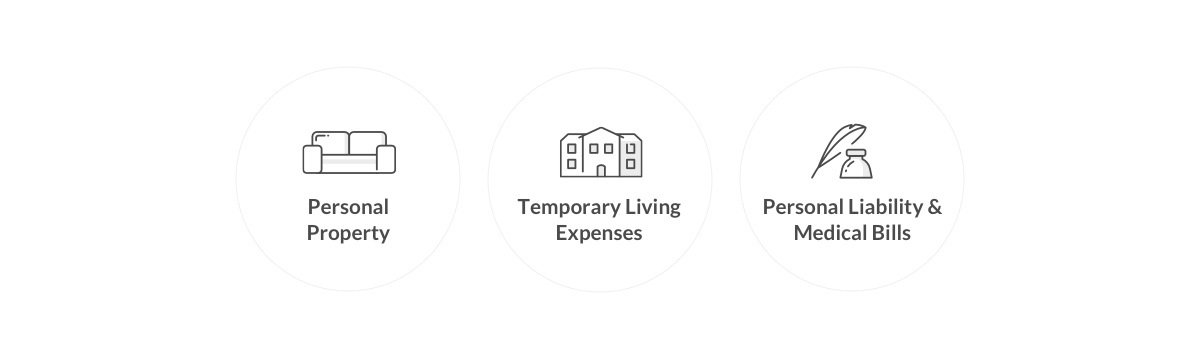
What does all that mean, exactly?
Personal property coverage pays to repair or replace your belongings when a covered peril damages, destroys, or steals them.
That includes clothes, furniture, electronics, collectibles, and jewelry. It might even include food that spoils after a covered loss.
For example, someone breaks into your apartment and takes your TV and speakers. Personal property coverage can help you replace them, up to your limit and after your deductible.
Standard policies cover named perils. That means the cause of the damage has to be on the list. The standard HO-4 list has 16 perils:
If your belongings are damaged by one of these, your policy can help cover the cost. If the cause isn’t on the list, it isn’t covered.
Loss of use pays for the extra costs of living somewhere else when a covered peril makes your place unlivable. “Additional” means costs beyond what you’d normally spend.
For example, a kitchen fire leaves your apartment unlivable for three weeks. Your policy can help with hotel bills, laundry, and the food costs that go beyond your usual grocery budget.
Keep your receipts. They make the claim faster.
Personal liability coverage helps pay legal fees and damages if you’re responsible for someone’s injury or for damage to their property.
It also extends to certain damage you cause away from home, like if you accidentally smash your friend’s pricey glass coffee table while visiting.
For example, your bathtub overflows while you’re out, and the water ruins your downstairs neighbor’s ceiling and rug. Liability coverage can help pay to fix both.
Medical payments to others helps pay a guest’s medical bills if they get hurt at your place in an accident, even if no one sues.
For example, a friend trips on your rug and breaks a wrist. Medical payments can help cover the ER bill, so it doesn’t turn into an awkward conversation or a lawsuit.
This coverage is for guests. It doesn’t cover you or the people who live with you.
Yes, in many cases. Your named perils follow your belongings, so theft counts whether it happens at home or elsewhere.
For example, if someone breaks into your locked car and steals your laptop, your renters policy can help replace it. Your car insurance wouldn’t cover the laptop, because it only covers the car itself.
Sublimits still apply. A stolen laptop falls under the portable electronics limit below.
A limit is the most your policy will pay for a coverage. A sublimit is a smaller cap on certain types of property inside that limit.
For instance, you can choose $10,000 of personal property coverage. If your apartment is robbed and all your belongings are taken, your insurer would pay up to that $10,000 limit, after your deductible.
A deductible is the amount you pay before your coverage pays. Say your deductible is $500 and you lose $3,000 of stuff. You’d get $2,500. (This is a made-up example, not a quote.)
Sublimits may vary by state:
For jewelry, other perils like fire fall under your full personal property limit. Cash works differently: the $200 limit applies to any covered peril.
One thing that trips people up: an Apple Watch counts as jewelry, not portable electronics, so the jewelry limit applies to it.
When you file a claim, your policy pays one of two ways:
For example, your four-year-old laptop is stolen. Replacement cost pays toward a new laptop. Actual cash value pays what a four-year-old laptop is worth, which is less.
Which one applies depends on your policy and state, so check your declarations page.
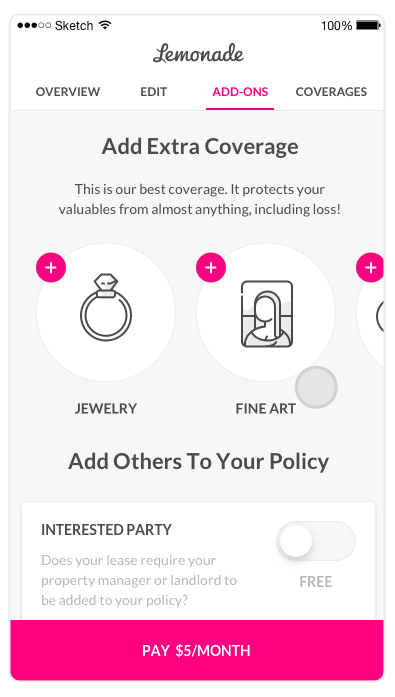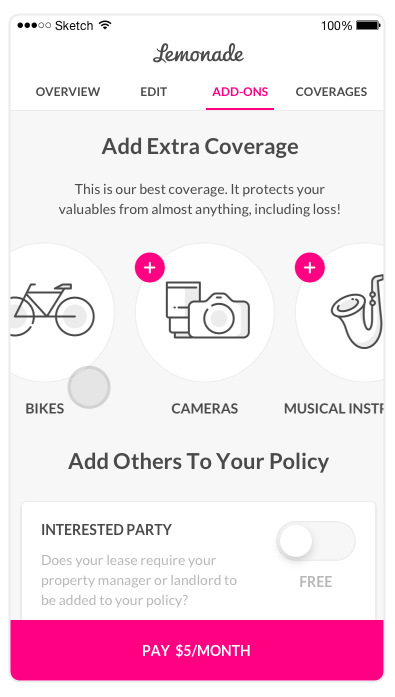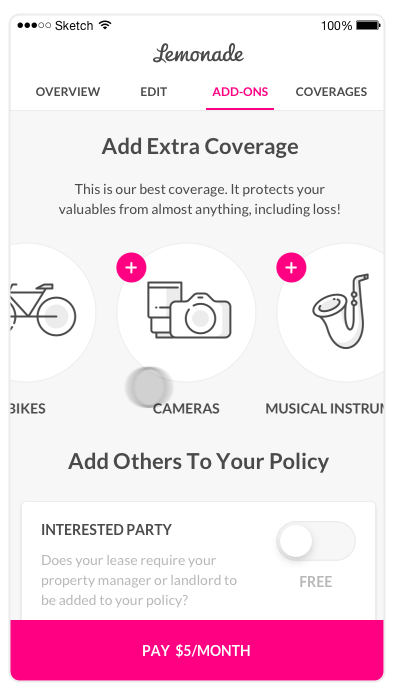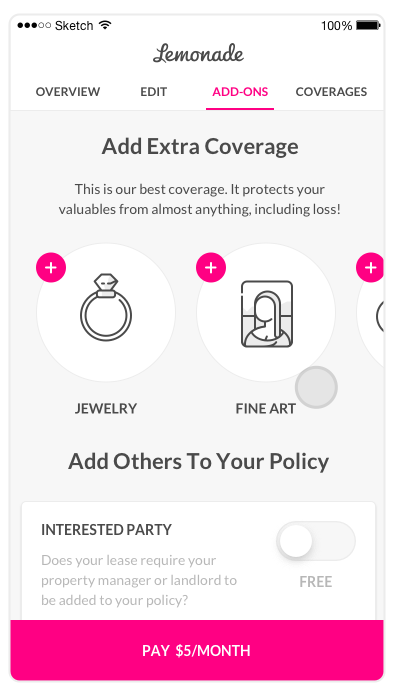
What if you want to boost the coverage you have for certain specific items that are especially valuable? In insurance terms, that extra protection is known as scheduled personal property coverage.
“Scheduled personal property coverage” is a real mouthful, so at Lemonade we call it Extra Coverage.
For an additional charge, you can apply to add it to jewelry and to valuables like bikes, cameras, fine art, and musical instruments.
These items already get some coverage on your base policy. Extra Coverage adds:
Some items may need an appraisal or proof of purchase. The process is simple in the Lemonade app.
Renters insurance is pretty awesome, but it’s not a cloak of invincibility. It won’t protect you from every crappy thing that can happen, so it helps to know what’s excluded.
These things aren’t covered:
Not sure how much coverage is right for you? Check out our easy guide to how much renters insurance you need.
Not on its own. Equipment Breakdown Coverage (EBC) is an add-on you can purchase for that.
Your basic renters policy protects your electronics and appliances against certain perils, but not against every type of damage.
Yes. You can change your coverage after you buy, including raising limits or adding Extra Coverage.
At Lemonade, you can make adjustments to coverage limits or your deductible via the app-although doing so could affect your monthly premium.You can also add additional insureds, add scheduled personal property coverage to valuable items (we call it Extra Coverage here at Lemonade), update your payment info, cancel a policy, purchase a new policy, and more.
Often. A student’s belongings in a dorm may be covered under a parent’s policy, but an off-campus apartment usually needs its own. Double-check with your insurer before assuming a student is fully protected.
Not if you use them to run a business. A personal laptop you use for a remote job is usually treated as personal property, but business equipment and inventory aren’t. If you’re unsure, ask support.
No. Everyday breakage and wear aren’t named perils. Extra Coverage can cover accidental damage to the valuables you schedule.
Renters insurance covers four main things. First, your personal belongings against named perils, typically 16 covered events depending on your state, including fire, theft, and sudden water damage. Second, liability coverage if you’re responsible for someone’s injury or property damage. Third, medical payments to others if someone gets hurt on your property. Fourth, loss of use coverage if your place becomes uninhabitable due to a covered loss. What it doesn’t cover: the building structure itself. That’s your landlord’s insurance. At Lemonade, all four are bundled into one policy. Read the full thread on Reddit
Yes, they protect against completely different things. Personal property coverage replaces your belongings if they’re stolen or damaged by a named peril. Liability coverage protects you if someone gets hurt in your place or you accidentally damage their property. At Lemonade, all four core coverages, personal property, liability, medical payments to others, and loss of use, are bundled into a single policy. Read the full thread on Reddit
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage may not be available in all states.
Please note: Lemonade articles and other editorial content are meant for educational purposes only, and should not be relied upon instead of professional legal, insurance or financial advice. The content of these educational articles does not alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. While we regularly review previously published content to ensure it is accurate and up-to-date, there may be instances in which legal conditions or policy details have changed since publication. Any hypothetical examples used in Lemonade editorial content are purely expositional. Hypothetical examples do not alter or bind Lemonade to any application of your insurance policy to the particular facts and circumstances of any actual claim.