
Car Insurance in Oak Harbor, WA
Not every Oak Harbor driver puts the same miles in. Maybe you work from home, or maybe SR-20 is somewhere you rarely find yourself. Either way, you shouldn’t pay a flat rate for miles you never drove.
Lemonade Pay Per Mile makes sure you don’t.
How much does car insurance
cost in Oak Harbor?
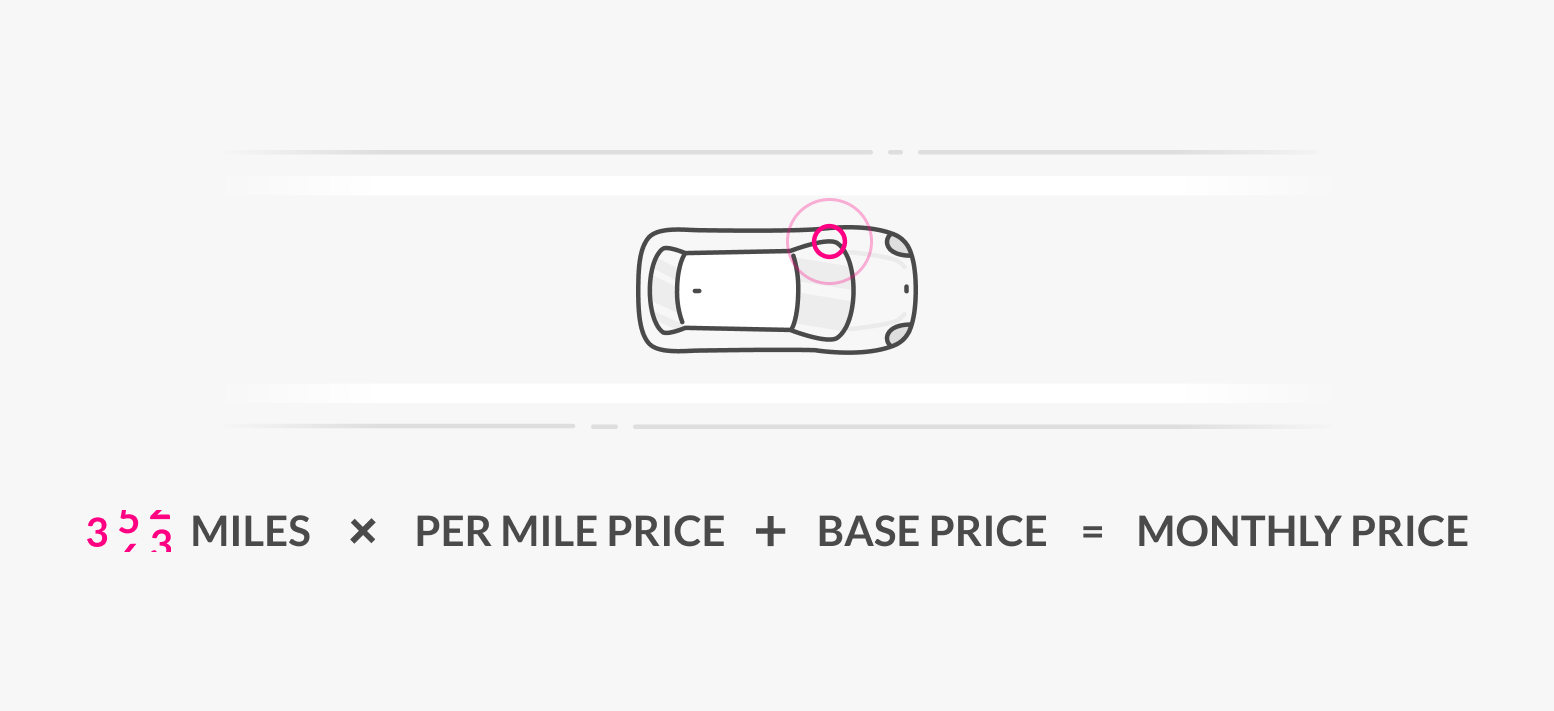
The average estimated cost of Lemonade car insurance in Oak Harbor ranges from roughly $2,280 to $2,340 per year*. You’ll pay a different price each month; it’s a calculation of the number of miles you drive multiplied by your per-mile price, plus your monthly base price that doesn’t change.
How can I get cheaper car insurance in Oak Harbor?
The savings don’t stop at signup. Here’s what else is on the table.
Bundle discounts
The more you bundle with Lemonade, the more you save. Car, renters, homeowners, pet, and more.
Safe driving
The safer you drive, the lower your premium. We look at things like speed, braking, and how smoothly you take turns.
Low mileage
The less you drive, the less you pay. Every month, no exceptions.
What is the minimum car insurance
required in Oak Harbor?
Every Oak Harbor driver needs to carry a minimum level of coverage to legally drive. Here’s exactly what Washington requires.
| Required minimum coverages for Tennessee drivers | Minimum amount required |
|---|---|
| Bodily injury liability | $25,000(per person)/ $50,000 (per accident) |
| Property damage liability | $10,000 |
What additional car insurance coverages
does Lemonade offer in Oak Harbor?
The state minimum covers the basics. These coverages help fill in the gaps.
Collision coverage
To repair or replace your own car if it’s damaged in an accident with another vehicle, or a stationary object (like a fence, highway divider, and so on).
Read moreComprehensive coverage
To fix damage to your car, or possibly replace it entirely, if there are damages or losses from an incident that didn’t involve a collision with another vehicle (like if you hit a deer, damage from a hailstorm, and so on).
Read morePersonal injury protection (aka PIP)
Can help pay for things like your medical bills, lost wages, and other related expenses after a car accident. With PIP, your own insurance company covers the medical expenses from a car accident regardless of who is at fault.
Read moreUninsured / underinsured motorist bodily injury coverage
Can help cover your medical bills and lost wages related to injuries caused by an uninsured or underinsured driver.
Read moreUninsured / underinsured motorist property damage coverage
Can help repair or replace your own car if you get into a car accident with an uninsured or underinsured driver.
Read moreTemporary transportation coverage
Transportation expenses like rideshares, public transportation, bike sharing, or a rental car for up to 30 days while your car is being repaired or appraised.
Read moreWhat’s the best car insurance in Oak Harbor?
Better pricing. Faster claims. Perks that actually matter.
Here’s what you get when your insurer is built on tech, not paperwork.
Priced for you
Most insurers average you in with everyone else. We don’t. Your price is built around how you drive. Not the driver next to you.
No hold music
Buy a policy, add a car, file a claim, update your coverage. All from the app, all in minutes.
Claims, not chaos
Open the app, tell us what’s going on, and we’ll take it from there. Fast, clear, and no runaround.
Beyond Oak Harbor: car insurance across Washington
Oak Harbor car insurance FAQs
What happens if you drive without insurance in Oak Harbor, WA?
Washington state requires all drivers to carry minimum liability coverage, and getting caught without it in Oak Harbor can mean fines, a suspended license, and having your car impounded. If you cause an accident while uninsured, you’re personally on the hook for the other driver’s costs. It’s a risk that tends to cost a lot more than just getting covered in the first place.
How does Oak Harbor's weather affect car insurance?
Oak Harbor sits in the Pacific Northwest, where wet winters, heavy fog off Puget Sound, and slick roads are just part of driving life. Comprehensive coverage can help protect your car from weather-related damage like flooding or falling branches, while collision coverage kicks in if slippery conditions lead to an accident. If you’re commuting through Island County in the rain, it’s worth making sure your coverage matches the conditions.
Is car insurance more expensive for younger drivers in Oak Harbor?
Younger drivers do tend to pay more on average, but safe driving habits can work in your favor and bring costs down below what age alone might suggest. Pay-per-mile insurance can also be a smart fit if you’re a younger driver who doesn’t rack up a lot of miles, like a student or part-time commuter in Oak Harbor.
What coverage options go beyond Washington's minimum requirements?
Washington’s state minimum only covers liability, meaning damage you cause to others, but it won’t pay for repairs to your own car or replace it if it’s totaled. Adding collision and comprehensive coverage fills those gaps, and you can also look at medical payments coverage if you want help with injury costs regardless of fault. Many Oak Harbor drivers find that a fuller coverage package gives them a lot more breathing room after an unexpected incident.
What should you do after a car accident in Oak Harbor?
First, make sure everyone is safe and call 911 if there are any injuries, especially on busier roads like State Route 20. Exchange insurance and contact info with the other driver, take photos of the scene, and file a police report if there’s significant damage. Then contact your insurance provider as soon as possible to start your claim.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage and discounts may not be available in all states. Lemonade Insurance analyzed policy rates to calculate average car premiums from Oct 2025 through September 2026. This analysis is based on Lemonade’s internal data and is meant for illustrative purposes only; quotes may vary depending on individual circumstances.
Continue Reading
How Much Does Car Insurance Cost in 2026?
Let’s dig into the factors that impact car insurance rates.
Pay Per Mile Car Insurance, Explained
Have stellar driving habits and spend less time behind the wheel than the average driver? Pay per mile car insurance could be a great fit.
Car Insurance for Electric Cars
We reward drivers for the environment-friendly driving choices they’re already making. Here are some of the perks.
Car Insurance in Redmond
Get an auto insurance quote in Redmond
Walla Walla, WA Car Insurance
Get an auto insurance quote in Walla Walla
Car Insurance in Bremerton
Get an auto insurance quote in Bremerton