
Car Insurance in Issaquah, WA
Not every Issaquah driver puts the same miles in. Maybe you work from home, or maybe I-90 is somewhere you rarely find yourself. Either way, you shouldn’t pay a flat rate for miles you never drove.
Lemonade Pay Per Mile makes sure you don’t.
How much does car insurance
cost in Issaquah?
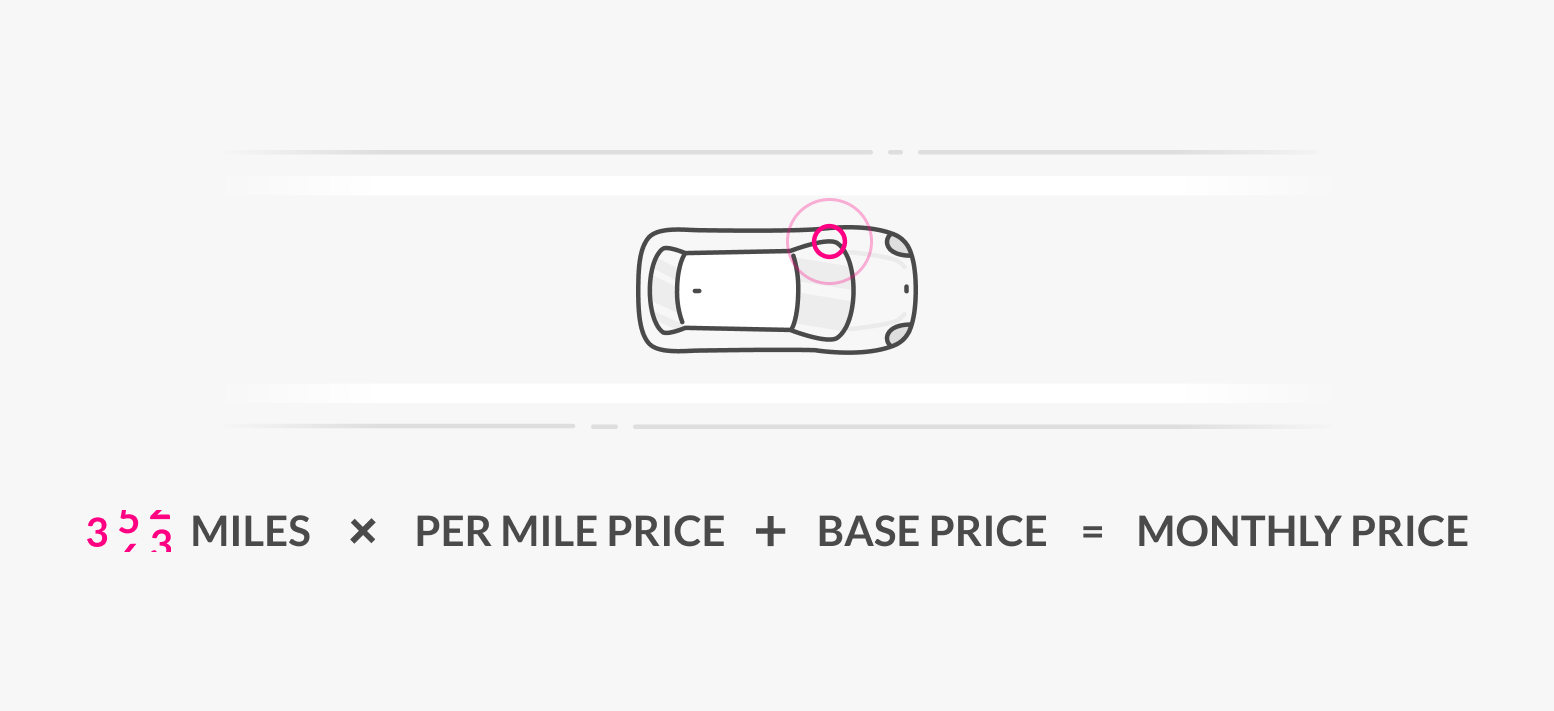
The average estimated cost of Lemonade car insurance in Issaquah ranges from roughly $2,340 to $2,400 per year*. You’ll pay a different price each month; it’s a calculation of the number of miles you drive multiplied by your per-mile price, plus your monthly base price that doesn’t change.
How can I get cheaper car insurance in Issaquah?
The savings don’t stop at signup. Here’s what else is on the table.
Bundle discounts
The more you bundle with Lemonade, the more you save. Car, renters, homeowners, pet, and more.
Safe driving
The safer you drive, the lower your premium. We look at things like speed, braking, and how smoothly you take turns.
Low mileage
The less you drive, the less you pay. Every month, no exceptions.
What is the minimum car insurance
required in Issaquah?
Every Issaquah driver needs to carry a minimum level of coverage to legally drive. Here’s exactly what Washington requires.
| Required minimum coverages for Tennessee drivers | Minimum amount required |
|---|---|
| Bodily injury liability | $25,000(per person)/ $50,000 (per accident) |
| Property damage liability | $10,000 |
What additional car insurance coverages
does Lemonade offer in Issaquah?
The state minimum covers the basics. These coverages help fill in the gaps.
Collision coverage
To repair or replace your own car if it’s damaged in an accident with another vehicle, or a stationary object (like a fence, highway divider, and so on).
Read moreComprehensive coverage
To fix damage to your car, or possibly replace it entirely, if there are damages or losses from an incident that didn’t involve a collision with another vehicle (like if you hit a deer, damage from a hailstorm, and so on).
Read morePersonal injury protection (aka PIP)
Can help pay for things like your medical bills, lost wages, and other related expenses after a car accident. With PIP, your own insurance company covers the medical expenses from a car accident regardless of who is at fault.
Read moreUninsured / underinsured motorist bodily injury coverage
Can help cover your medical bills and lost wages related to injuries caused by an uninsured or underinsured driver.
Read moreUninsured / underinsured motorist property damage coverage
Can help repair or replace your own car if you get into a car accident with an uninsured or underinsured driver.
Read moreTemporary transportation coverage
Transportation expenses like rideshares, public transportation, bike sharing, or a rental car for up to 30 days while your car is being repaired or appraised.
Read moreWhat’s the best car insurance in Issaquah?
Better pricing. Faster claims. Perks that actually matter.
Here’s what you get when your insurer is built on tech, not paperwork.
Priced for you
Most insurers average you in with everyone else. We don’t. Your price is built around how you drive. Not the driver next to you.
No hold music
Buy a policy, add a car, file a claim, update your coverage. All from the app, all in minutes.
Claims, not chaos
Open the app, tell us what’s going on, and we’ll take it from there. Fast, clear, and no runaround.
Issaquah drivers, by the numbers
Issaquah roads have a story to tell. Here’s what our data found.
Beyond Issaquah: car insurance across Washington
Issaquah Washington car insurance FAQs
What type of car insurance coverage is recommended for Issaquah’s weather conditions?
Comprehensive coverage is a must for Issaquah drivers due to frequent rain, occasional snow, and risks of falling branches from windstorms. It protects your vehicle from non-collision weather-related damages like flooding or debris.
How does Issaquah’s proximity to the Cascades affect car insurance needs?
The nearby mountain region increases the likelihood of icy roads and challenging driving conditions in winter. Collision coverage provides protection in case of accidents caused by these elevated risks.
What happens if I don’t have the minimum car insurance coverage required in Issaquah?
Driving uninsured in Issaquah can result in a fine of $550 or more. Your driving privileges might also be suspended, potentially disrupting your ability to carry out daily activities. Keeping your insurance up to date helps you avoid these penalties and remain compliant with the law.
Is Washington an at-fault state?
Washington operates under an at-fault system, so in Issaquah, the driver deemed at fault for a crash is financially responsible. This typically happens through their auto insurance or personal payments.
How can I lower my car insurance premium in Issaquah?
You can lower your car insurance premium by maintaining a clean driving record (Lemonade drivers in Issaquah can get the three year safe driving discount), opting for higher deductibles, and considering bundling your car insurance with other types of insurance.
Lemonade offers renters insurance, condo insurance, pet insurance, and life insurance in Issaquah that you can bundle with a Lemonade car insurance policy, and bundling any combination of our insurance products together will unlock savings.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage and discounts may not be available in all states. Lemonade Insurance analyzed policy rates to calculate average car premiums from Oct 2025 through September 2026. This analysis is based on Lemonade’s internal data and is meant for illustrative purposes only; quotes may vary depending on individual circumstances. Claims statistics reflect Lemonade Car claims filed in Washington between October 2025 and September 2026; all figures are based on Lemonade’s internal claims data, intended for illustrative purposes only, and may not be representative of all Washington drivers or the broader insurance market.
Continue Reading
How Much Does Car Insurance Cost in 2026?
Let’s dig into the factors that impact car insurance rates.
Pay Per Mile Car Insurance, Explained
Have stellar driving habits and spend less time behind the wheel than the average driver? Pay per mile car insurance could be a great fit.
Car Insurance for Electric Cars
We reward drivers for the environment-friendly driving choices they’re already making. Here are some of the perks.
Car Insurance in Marysville
Get an auto insurance quote in Marysville
Car Insurance in Tacoma
Get an auto insurance quote in Tacoma
Car Insurance in Lacey
Get an auto insurance quote in Lacey