
Russian Blue Pet Insurance
Reserved, loyal, and worth every bit of patience it takes to earn their trust.
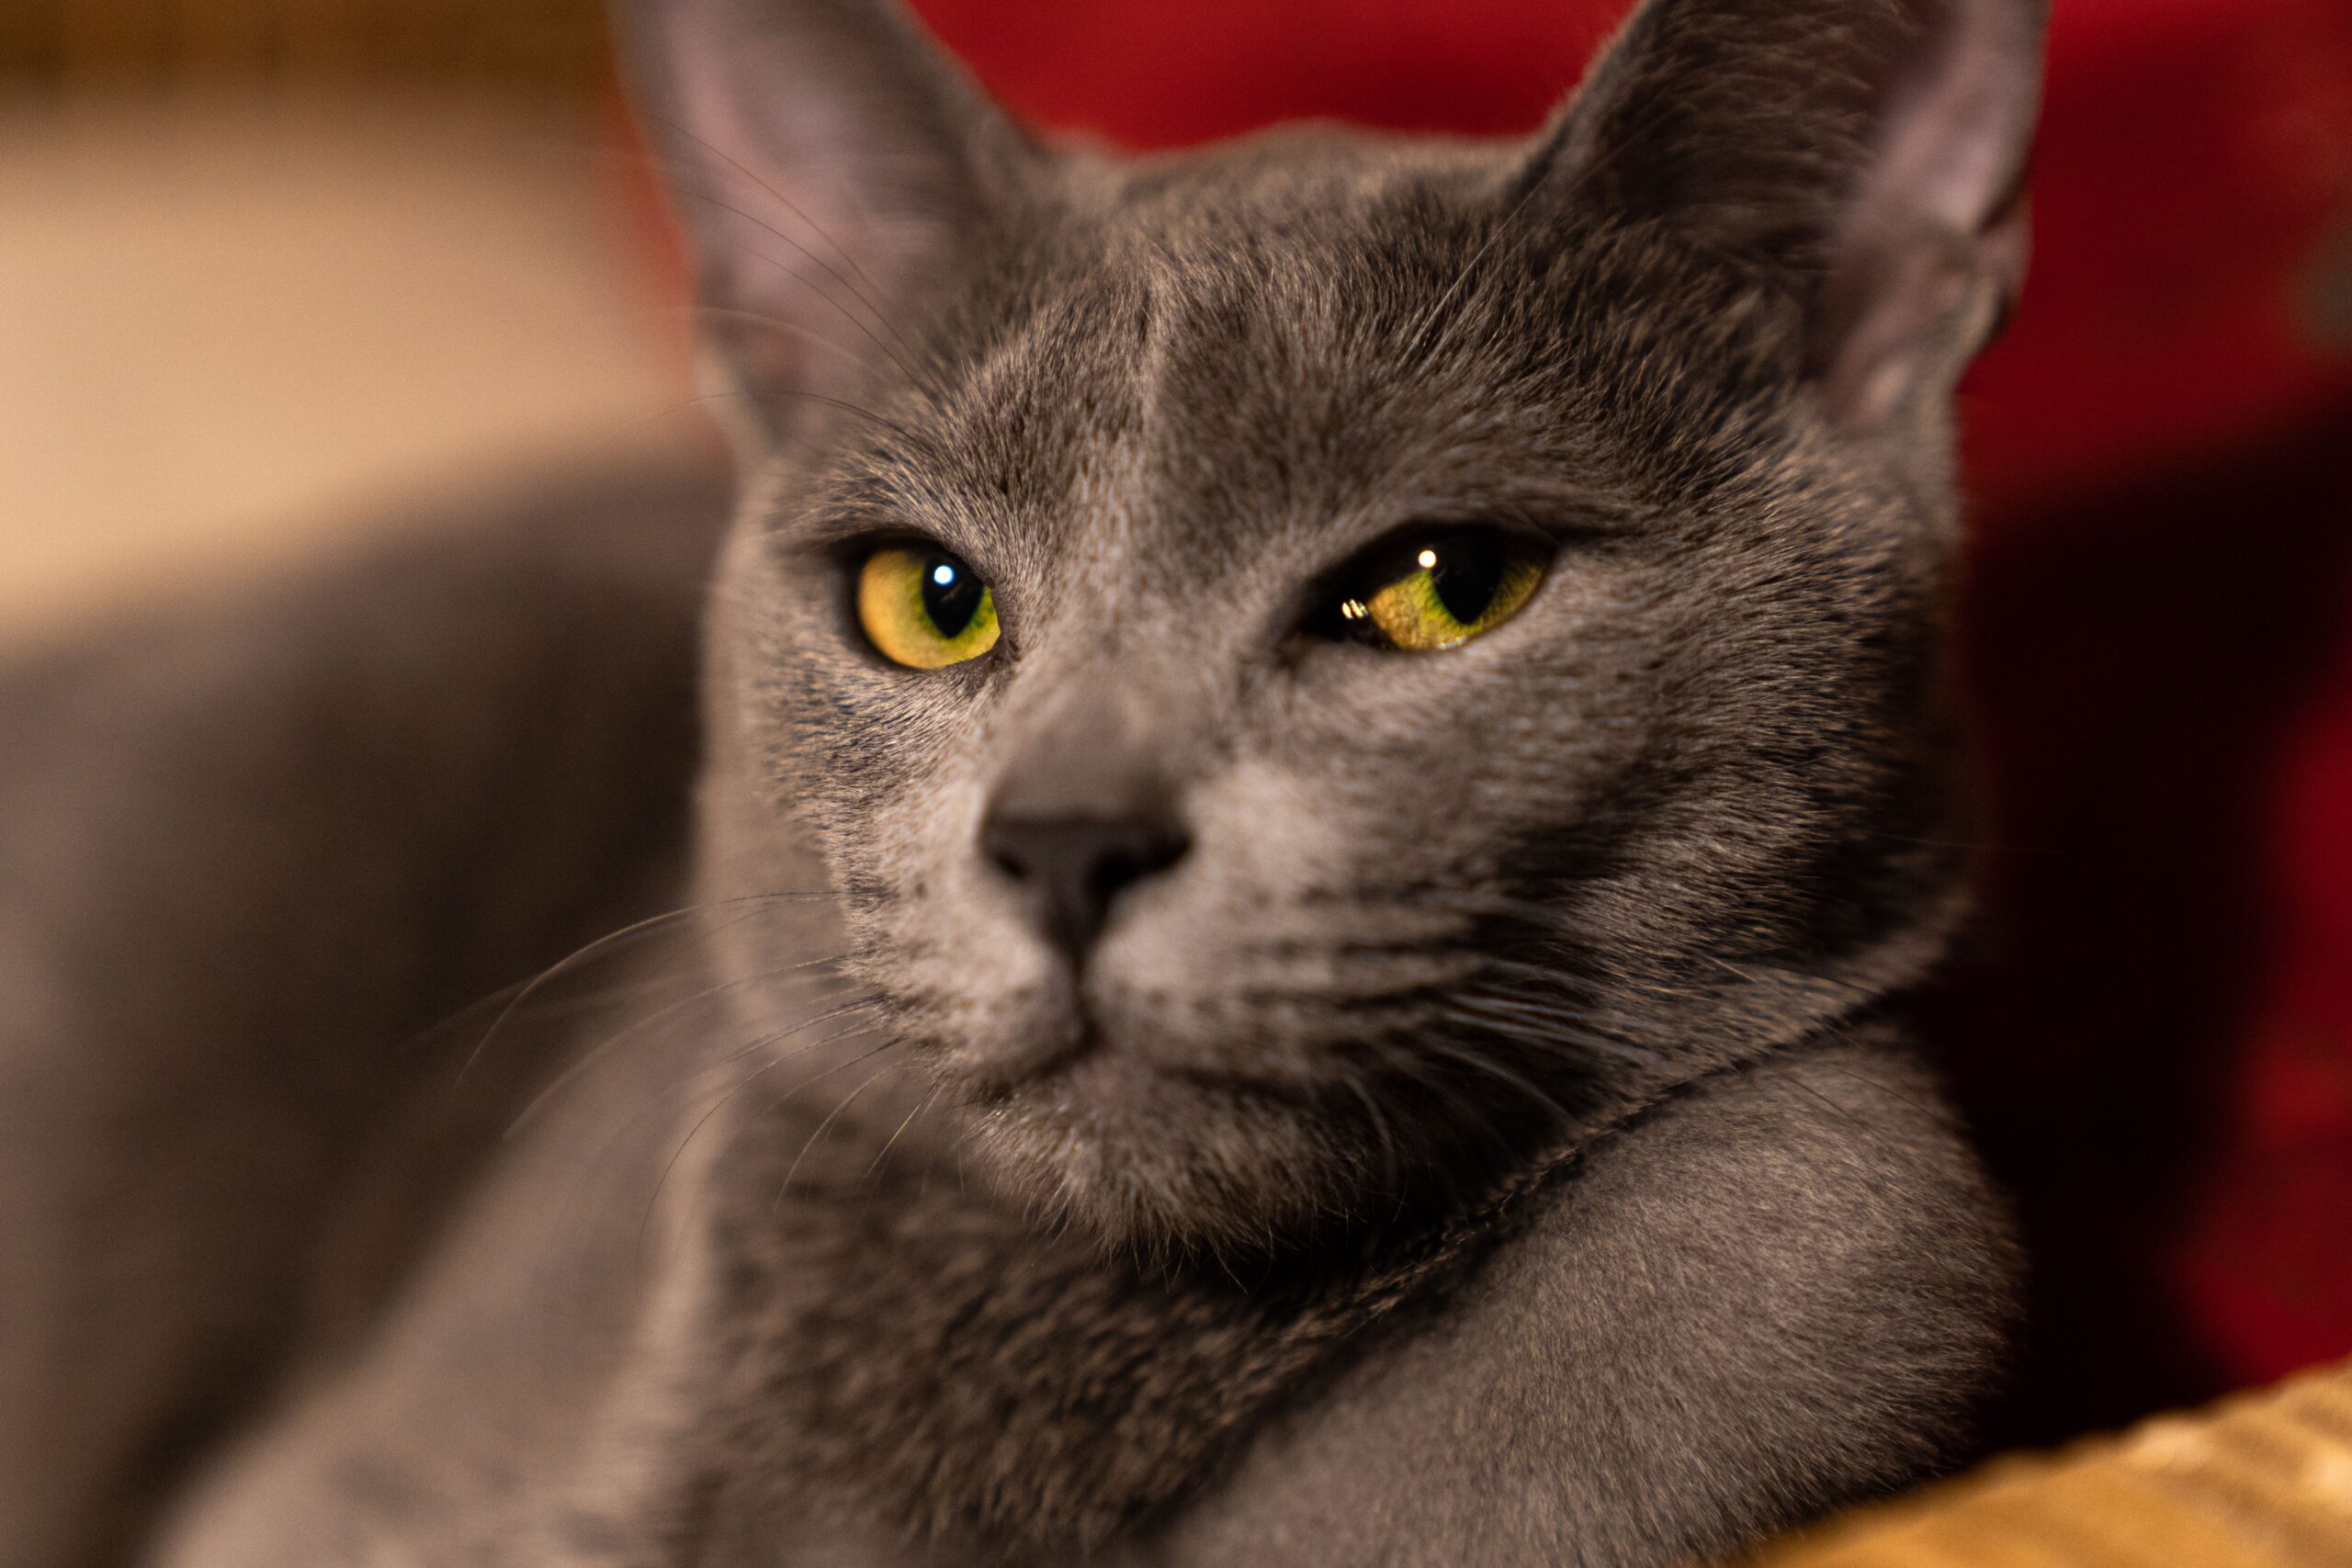
Reserved, loyal, and worth every bit of patience it takes to earn their trust.
Russian Blues aren’t the cat that warms up to everyone. They’re selective, observant, and take their time. But once they decide you’re their person, that bond is total. They’re also a breed with a handful of health predispositions, particularly around their urinary tract, that are worth getting ahead of before a vet bill makes the introduction.
 TL;DR
Russian Blues are gentle, reserved, and generally healthy cats. But this is a breed with a well-documented set of predispositions, particularly around the urinary tract, and several of them share overlapping symptoms that can be easy to miss until things escalate. None of them are guaranteed, but all of them are worth knowing about before a surprise vet bill makes the introduction.
Calcium oxalate crystals form in the urinary tract, causing discomfort and blockages. They cannot be dissolved with diet alone, making early detection and veterinary intervention important.
Learn more about calcium oxalate urolithiasisDiabetes occurs when the body can't regulate blood sugar. Russian Blues can be predisposed, particularly if overweight, making a measured diet and regular vet checkups important.
Learn more about DMFLUTD covers conditions affecting the bladder and urethra. Signs include straining to urinate, bloody urine, or frequent litter box visits. Male cats face a higher risk of blockages.
Learn more about FLUTDPRA causes gradual retinal deterioration, leading to vision loss and eventual blindness. Russian Blues carry a known genetic risk and should be screened early with an ophthalmic exam.
Learn more about PRAYour vet will likely recommend a complete blood count, biochemistry profile, urinalysis, and FIV/FeLV screening at your Russian Blue’s annual checkup. For this breed specifically, it’s worth asking about a urine culture and urinalysis at every visit. Urinary tract disease is one of the more common conditions in Russian Blues, and catching it early makes treatment significantly more manageable.
The numbers below aren’t projections. They’re what Russian Blue owners actually filed and got back last year.
Behind each of those numbers is a Russian Blue owner who had a plan in place when an unexpected accident or illness struck. Here’s what that can look like in practice.
Shadow, a 5-year-old Russian Blue, had always been particular about his litter box. His owner noticed him making more trips than usual, with little to show for it. A vet visit, urinalysis, and urine culture later: a confirmed FLUTD diagnosis and a $620 bill.
With a $250 deductible, 80% co-insurance, and a $20,000 annual limit:
With the deductible now met for the year, every eligible claim that follows gets the full 80%.
Shadow starts drinking more water than usual and losing weight. Bloodwork confirms diabetes. His owner leaves with an insulin prescription, a glucose monitoring plan, and a $480 bill.
With the deductible already met:
Two claims. One cat. One year. Without coverage: $1,100 out of pocket. With Lemonade: $470.
Shadow is doing well, by the way.
You’ve seen the risks. You’ve seen what a couple of claims in a single year can look like. Here’s how to build a plan around your cat.
Every Lemonade policy starts with accident and illness coverage as the base. That means diagnostics, medications, and treatments for unexpected accidents and illnesses that aren’t pre-existing and occur after your waiting periods have passed. Waiting periods are the short windows between when your policy starts and when coverage kicks in, just long enough to make sure a condition is genuinely new.
From there, you set your deductible, co-insurance, and annual limit. Your co-insurance is the percentage Lemonade covers of each eligible vet bill. Your deductible is what you pay before reimbursement kicks in. Your annual limit is the most Lemonade will pay out in a policy year. You saw how those three numbers work together in Shadow’s story.
Once your base is set, add what makes sense for your Russian Blue and skip what doesn’t.
Russian Blues are prone to urinary conditions and diabetes, both of which can develop quietly before any obvious symptoms appear. Staying consistent with annual exams, bloodwork, and urinalysis is how you catch them early. A routine care package reimburses you for the preventive visits and tests you’re already doing.
What’s available varies depending on where you live, so the easiest way to see your options is to get a quote.
When your Russian Blue sees a vet for an accident or illness, there are typically two costs: the actual treatment, and the exam fee your vet charges for their time. Your base policy covers the treatment. Without this add-on, that exam fee comes straight out of pocket.
Remember Shadow’s FLUTD visit? That $620 bill included a $75 exam fee. Here’s what the reimbursement looks like with and without the add-on:
| Without visit fee add-on | With visit fee add-on | |
|---|---|---|
| Eligible amount | $545 | $620 |
| Apply co-insurance (80%) | $436 | $496 |
| Subtract deductible ($250) | $186 | $246 |
| You pay | $434 | $374 |
That’s $60 more back in your pocket on a single visit. It’s a small difference on its own, but it can really add up if your cat needs ongoing or repeat care.
This add-on is subject to your base policy’s co-insurance and deductible, and covers exam fees for accident and illness visits only. It doesn’t apply to annual wellness exams, routine preventive care, or anything related to a pre-existing condition.
Your base policy covers diagnostics and treatment when something goes wrong. This add-on picks up where that leaves off, covering rehabilitation and physical therapy for functionality issues that result from an unexpected accident or illness. Russian Blues are quiet, deliberate movers, but that doesn’t make them immune to injury. A soft tissue injury, a post-surgical recovery, or joint stiffness developing with age can all benefit from structured rehabilitation.
Take Shadow again. Say he injures a hind leg and needs surgery to address the damage. His base policy covers the diagnosis and surgery. Here’s what happens to the rehabilitation bill with and without the add-on:
| Initial treatment | PT without add-on | PT with add-on | |
|---|---|---|---|
| Eligible amount | $1,400 | $0 (PT not covered) | $600 |
| Deductible | Already met | N/A | Already met |
| Apply co-insurance (80%) | $1,120 | N/A | $480 |
| You pay | $280 | $600 | $120 |
That’s a $480 difference, just on the recovery. The add-on doesn’t cover alternative treatments like CBD or aromatherapy, or anything related to a pre-existing condition.
Russian Blues can develop dental disease gradually over time, and it’s one of those things that’s easy to overlook until it becomes painful and expensive. Lemonade offers two dental add-on options depending on where you live.
Dental illness: Covers treatments, procedures, diagnostics, and medications for dental illness, including extractions, dental surgeries, and conditions like gingivitis and periodontal disease. Subject to your policy’s co-insurance and deductible, with a $1,000 annual limit. Routine cleanings aren’t included here, but may be available through a preventive care package depending on your state.
Dental care: Everything in dental illness, plus routine dental cleanings. Pre-existing dental conditions are covered under this option, and no deductible applies. Also comes with a $1,000 annual limit, and is available to add if your Russian Blue is between 0 to 3 years old.
Russian Blues are creatures of habit. They thrive on calm, consistency, and a home environment that doesn’t change much. When something disrupts that, a new pet, a move, a shift in routine, the response is rarely obvious. Russian Blues tend to withdraw rather than act out, which means anxiety and stress-related conditions can quietly take hold before an owner realizes something is wrong.
This add-on covers diagnostics, vet-recommended treatments, and medications for eligible behavioral conditions, including therapy sessions and specialized training for separation anxiety, phobias, and destructive or aggressive behaviors. Treatment must be administered by a vet or licensed behaviorist, and it’s subject to your base policy’s co-insurance and deductible, with a separate $1,000 annual limit.
General obedience training, pre-existing behavioral conditions, alternative treatments like CBD, and property damage aren’t covered. Visit fees for behavioral appointments fall under the base policy for those with the visit fee add-on.
Nobody wants to think about this one. But losing a pet is one of the hardest things a pet parent goes through, and the practical decisions that come with it shouldn’t have to be made under financial pressure in an already devastating moment.
This add-on covers vet-recommended euthanasia, cremation, and commemorative items, like an urn, framed paw prints, digital photo storage, or even a tattoo. It’s not subject to your base policy’s co-insurance or deductible, has an up to $500 limit, and still provides coverage if euthanasia is vet-recommended as the result of a pre-existing condition.
Funeral or burial costs and preservation services aren’t covered, and like most add-ons, it’s subject to a waiting period that varies by state.
Russian Blues form deep, lasting bonds with their people. This add-on won’t make that day easier. But it can make it a little less complicated.
The cost of your premium is personal. It depends on your cat’s age, your location, and what add-ons you select. One thing worth knowing: the earlier you enroll, the more coverage you have. Conditions that develop after your policy is active and waiting periods have passed are eligible for coverage. Conditions that exist before you enroll aren’t. For a breed with the Russian Blue’s health profile, that distinction matters.
| Age | Average monthly premium |
|---|---|
| 1 year old | $20–$25 |
| 2 years old | $20–$25 |
| 3 years old | $20–$25 |
| 4 years old | $20–$25 |
| 5 years old | $20–$25 |
| 6 years old | $25–$30 |
| 7 years old | $25–$30 |
Every pet insurance provider covers the basics, but Russian Blues have a specific set of needs that go beyond the basics. A breed this sensitive, with predispositions to urinary conditions, diabetes, and stress-related behavioral issues, needs a plan that’s built around them, not a one-size-fits-all policy.
With Lemonade, you’re not choosing from a fixed menu. You’re building a plan around your cat’s actual risk profile, adding urinary-related illness coverage for a breed that needs consistent monitoring, behavioral treatment for a cat that doesn’t handle change well, and routine vet care to stay ahead of conditions that develop quietly. And when you do need to file a claim, you can do it in the app in minutes.
Don’t just take our word for it. Here’s how we stack up:


The Russian Blue is believed to have originated in the port city of Arkhangelsk in northern Russia, where its thick double coat developed as natural protection against the harsh Arctic climate. Sailors are thought to have brought the breed to Western Europe in the 1860s, where it quickly attracted attention for its striking silvery-blue coat and vivid green eyes. It was first exhibited at the Crystal Palace in London in 1875 under the name Archangel Cat. After World War II, Scandinavian breeders introduced Siamese bloodlines to preserve the population, giving the modern Russian Blue its more refined, angular appearance. The Cat Fanciers Association officially recognized the breed in 1949.
Russian Blues are cautious, observant, and deeply loyal once they decide you’ve earned it. They won’t rush the process. In the early weeks, expect a cat that watches from a distance, takes stock of their environment, and moves at their own pace. That patience pays off. Once a Russian Blue bonds, they’re devoted in a way that’s quiet but unmistakable. They’ll follow you from room to room, seek you out when things feel uncertain, and settle nearby without demanding attention. They do best in calm, consistent households and don’t adapt well to frequent changes or loud, chaotic environments. If you’re looking for a cat that’s low-drama, deeply loyal, and content with a steady routine, there’s very little that compares.
Russian Blues are reserved, loyal, and one of the most quietly devoted cats you’ll ever share your home with. They’re also a breed with real health considerations that are worth getting ahead of. Whether you’re already living with one or still thinking about it, the right coverage means you can focus on building that bond, not worrying about the bills.
For most owners, yes. Russian Blues are prone to urinary conditions and diabetes, both of which can be expensive to diagnose and manage over time. Lemonade paid out $1.3M in Russian Blue claims last year, with an average payout of $441 per claim. Having coverage in place before something goes wrong is what turns a stressful vet bill into a manageable one.
Russian Blues are commonly predisposed to calcium oxalate urolithiasis, feline lower urinary tract disease, diabetes mellitus, and progressive retinal atrophy. Many of these conditions share overlapping symptoms, which is why consistent annual screening and early detection matter so much for this breed.
As early as possible. Conditions that develop after your policy is active and waiting periods have passed are eligible for coverage. Conditions that exist before you enroll or during your waiting periods are considered pre-existing and won’t be covered. Getting a plan in place before any health issues arise gives your Russian Blue the broadest possible coverage.
Yes, as long as the condition isn’t pre-existing and develops after your waiting periods have passed. That includes conditions Russian Blues are prone to, like FLUTD, calcium oxalate urolithiasis, and diabetes. Your base policy covers diagnostics, medications, and treatments, and add-ons let you extend that coverage to dental illness, behavioral conditions, and more.
Yes, but keep in mind that any conditions already present before your policy starts won’t be eligible for coverage. Premiums do increase with age, but coverage at any age can still make a meaningful difference on vet bills.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of the policies issued, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage may not be available in all states. Please note that statements about coverages, policy management, claims processes, Giveback, and customer support apply to policies underwritten by Lemonade Insurance Company or Metromile Insurance Company, a Lemonade company, sold by Lemonade Insurance Agency, LLC. The statements do not apply to policies underwritten by other carriers. Insurance claim data figures reflect approved accident and illness claims filed by Lemonade Pet policyholders over the trailing 12 months as of June 2026. They are averages across Lemonade’s insured population for this breed, not predictions of future claims or reimbursement for any individual pet. Actual payouts depend on your policy’s limit, deductible, co-insurance, waiting periods, and exclusions, and may not reflect the broader breed population or other insurers’ experience. Average insurance premium data is based on Lemonade’s internal data and reflects the average premium over the last 12 complete months, accurate as of June 2026.
Please note: Lemonade articles and other editorial content are meant for educational purposes only, and should not be relied upon instead of professional legal, insurance or financial advice. The content of these educational articles does not alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. While we regularly review previously published content to ensure it is accurate and up-to-date, there may be instances in which legal conditions or policy details have changed since publication. Any hypothetical examples used in Lemonade editorial content are purely expositional. Hypothetical examples do not alter or bind Lemonade to any application of your insurance policy to the particular facts and circumstances of any actual claim.