
- Are retaining walls covered by homeowners insurance?
- What retaining wall damage is covered?
- Why isn't retaining wall failure usually covered?
- Retaining wall scenarios: covered or not?
- Does homeowners insurance cover erosion and landslides?
- Does the material of a retaining wall affect coverage?
- How much coverage do you need for a retaining wall?
- What if a retaining wall damages your house or a neighbor's property?
- Do you need to tell your insurer when you build a retaining wall?
- Should you file a claim for retaining wall damage?
- How to file a retaining wall claim
- How to protect your retaining wall
- Before we go
- Retaining walls FAQs
Sometimes. Other structures coverage on your homeowners policy can pay for a retaining wall, but it depends on what damaged it, not the wall itself.
If a tree falls on it, lightning strikes, a fire starts, a windstorm hits, or a car crashes into it, you’re usually covered. Flooding, shifting soil, built-up water, poor construction, or old age usually aren’t. Homeowners insurance is built for sudden accidents, not slow or ground-related problems.
 TL;DR
- Retaining walls are usually covered as “other structures,” but only for covered events.
- Earth movement, erosion, landslides, mudslides, and floods are generally not covered.
- One limit is shared by all your detached structures, so a costly wall can use it up fast.
- Wear and tear, poor drainage, and poor construction generally aren’t covered either.
- Take photos of your wall and check your limit now, before you need to file a claim.
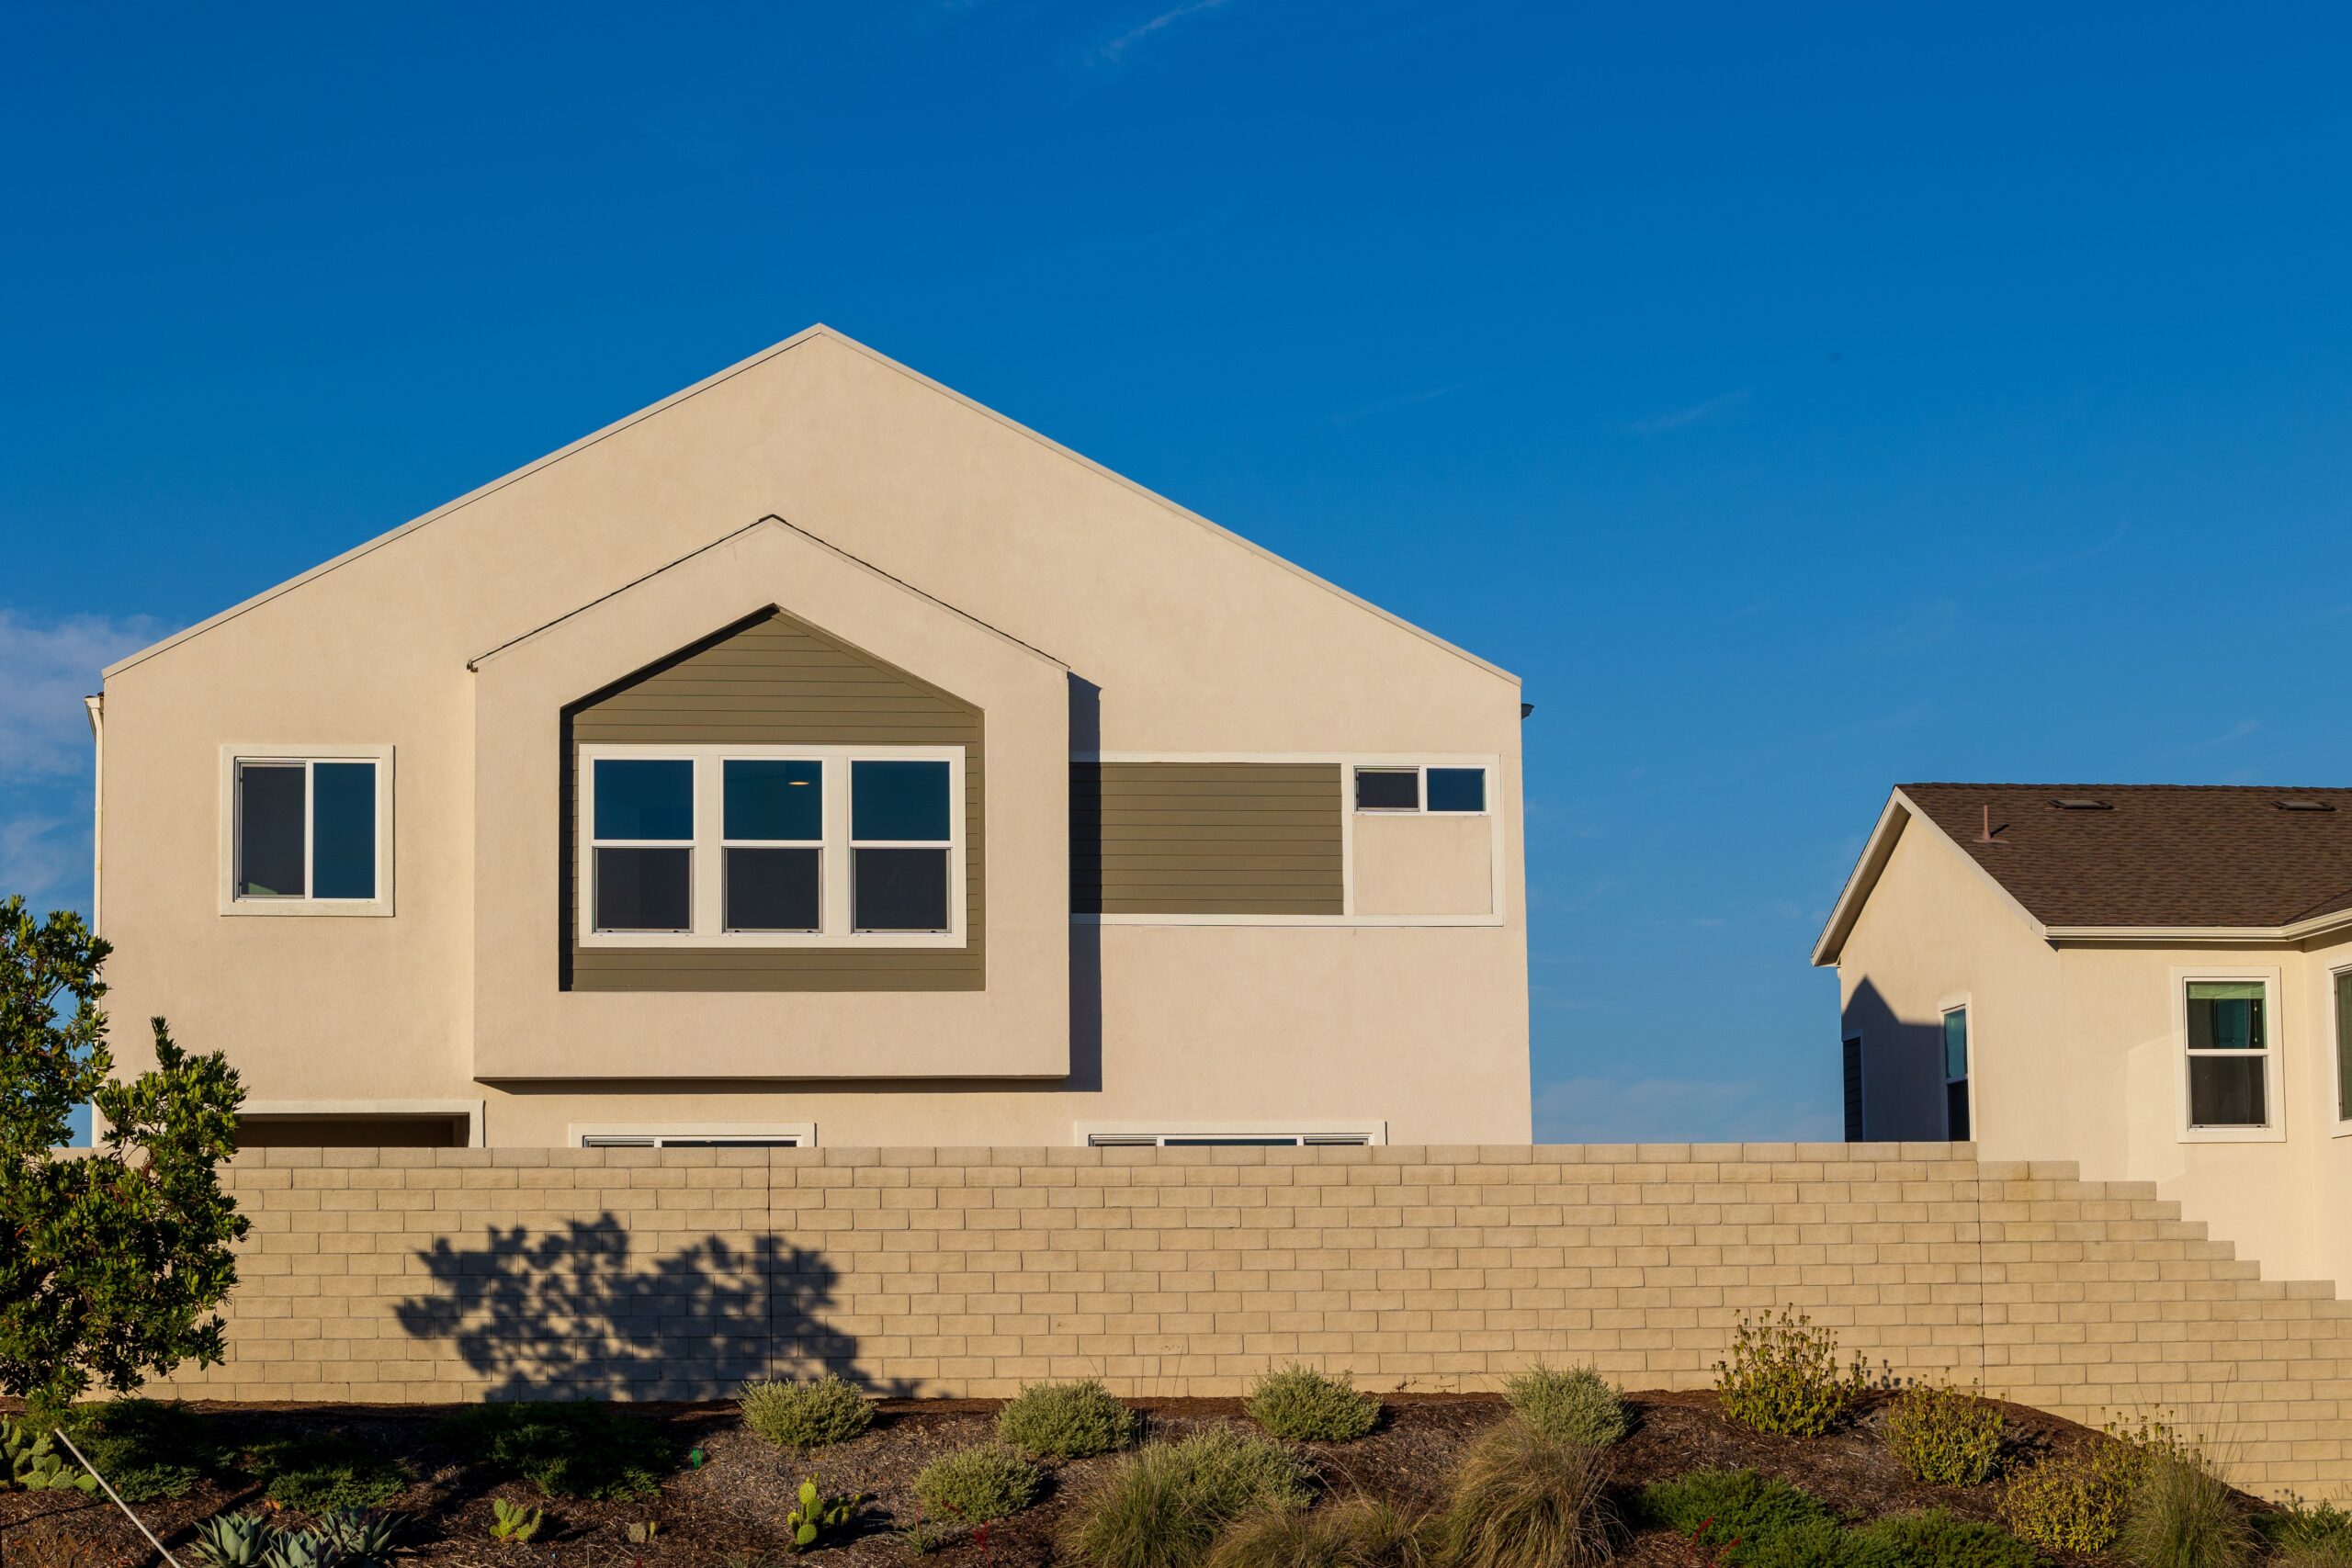
Are retaining walls covered by homeowners insurance?
Usually, yes, with some conditions.
Most homeowners policies treat a freestanding retaining wall as a detached structure. That puts it under Coverage B, also called other structures coverage. Lemonade’s homeowners policy covers other structures for any sudden, accidental damage unless the policy specifically excludes the cause.
Coverage B is shared with your fences, sheds, gazebos, and detached garages. It’s usually capped at 10% of your dwelling coverage (Coverage A, the limit for your house itself). With Lemonade, you can raise it to 30% of Coverage A. For more on how this works, see our guide to other structures coverage and our article on fences, which follow the same rules.
A wall that’s attached to your home, or holds up part of it, may be treated differently from a freestanding landscape wall. If that’s your situation, check with us.
| Wall type | How it’s typically treated | Notes |
|---|---|---|
| Freestanding landscape wall | Other structures (Coverage B) | Covered for sudden damage from a covered event |
| Wall holding back a slope | Other structures (Coverage B) | These usually fail because of soil, water, or construction, which are generally excluded |
| Wall attached to the house | May count as part of your home | Check with us to confirm |
| Boulder or gabion wall (stones held in a wire cage) | Other structures (Coverage B) | Same cause-of-damage rules apply |
| Timber wall | Other structures (Coverage B) | Rot, insects, and age aren’t covered |
What retaining wall damage is covered?
Coverage B protects against sudden, accidental damage unless an exclusion applies. Here’s what’s usually covered:
- Hail
- A fallen tree, unless it was a known hazard you ignored
- Fire
- Lightning
- Windstorm
- A car crashing into the wall
- Vandalism
- Weight of snow or ice, depending on your policy wording and how the damage happened
Did you know?
Hail is the #1 cause of other structures claims at Lemonade, at 40.7%. That’s based on claims covering things like fences, sheds, and retaining walls. (Based on internal Lemonade Homeowners insurance data, as of November 2026.)
Why isn’t retaining wall failure usually covered?
This is where most homeowners get surprised. Retaining walls hold back soil and water, and homeowners policies usually exclude both of those forces. Here’s what’s usually left out:
- Earth movement: soil sinking, heaving, or shifting, plus landslides and mudslides
- Water and flood: surface water, flooding, and pressure building up behind the wall
- Erosion: soil that washes away little by little
- Drainage failure
- Poor design or construction
- Wear and neglect: deterioration, settling, and age
- Earthquakes
Say your wall bulges or fails after heavy rain. That’s often not covered, because the cause is usually moving soil, surface water, or slow wear. Your policy wording and the facts of your loss matter, and an adjuster makes the final call.
Pro Tip
Good drainage is the best protection a wall has. Weep holes (small gaps that let water out), gravel backfill, and clear gutters relieve the pressure behind most failures. Those failures are also the ones insurance usually won’t pay for.
| Usually covered | Usually not covered |
|---|---|
| Fallen tree, fire, lightning | Earth movement, landslides, mudslides |
| Windstorm, hail | Flood and surface water |
| Car crash, vandalism | Erosion and drainage failure |
| Wear, settling, poor construction | |
| Earthquakes |
Retaining wall scenarios: covered or not?
Here are the most common ways a retaining wall gets damaged, whether it’s usually covered, and your next step in each case.
| What happened | Usually covered? | Why | What to do |
|---|---|---|---|
| A tree falls on the wall | Usually | Sudden damage from a covered event, unless the tree was a known, ignored hazard | Photograph the tree and wall, then file a claim |
| A car crashes into the wall | Usually | Car impact is a covered event | Get a police report if you can, then file |
| Lightning hits the wall | Usually | Covered event | Take photos, then file |
| Fire damages the wall | Usually | Covered event | Make the area safe, then file |
| Vandalism | Usually | Covered event | File a police report, then file your claim |
| Wall bulges after heavy rain | Usually not | Water pressure, moving soil, and drainage problems are the usual causes, and none are covered | Take photos, add temporary drainage, and ask for an assessment |
| Wall collapses in a landslide or mudslide | Usually not | Earth movement isn’t covered | Contact us, and call an engineer |
| Flood washes the wall away | Usually not | Flood policies generally exclude retaining walls | Check your flood policy |
| Frost pushes the wall out | Usually not | Expanding soil counts as earth movement, and the damage is gradual | Repair it early |
| Tree roots push blocks out | Usually not | Gradual damage | Manage the roots and fix small shifts |
| Wall leans as it settles | Usually not | Settling and wear and tear aren’t covered | Get a professional assessment |
| Wall fails from poor drainage | Usually not | Drainage and construction problems aren’t covered | Fix the drainage first |
| Earthquake damage | Usually not | Not covered unless you have earthquake coverage | Check your earthquake policy |
Every answer depends on your policy wording and the facts of the loss.
Does homeowners insurance cover erosion and landslides?
A homeowners policy usually won’t cover, since retaining walls are generally excluded. Earthquake coverage may pay if shaking damages your wall, depending on what your policy says. Neither one typically covers erosion, and landslides and mudslides may fall outside both.
| For your wall | Base policy | Flood policy | Earthquake policy |
|---|---|---|---|
| Erosion | Not covered | Generally exclude retaining walls | Generally not covered |
| Landslide or mudslide | Not covered | May not be covered | May not be covered |
| Flood damage | Not covered | Generally not covered | Not covered |
| Earthquake damage | Not covered | Not covered | May be covered, depending on the policy |
Detached structure coverage varies a lot, so read your flood and earthquake policy terms directly.
Does the material of a retaining wall affect coverage?
Not really. Coverage depends on the cause of damage. Material does change how likely damage is, what the fix costs, and how easy it is to document.
Whether a claim pays at replacement cost (what it costs to rebuild today) or actual cash value (replacement cost minus depreciation) depends on your policy. Check your loss settlement terms.
| Material | Typical weak spot | What to know |
|---|---|---|
| Poured concrete | Cracking, pressure from poor drainage | Keep engineering records and photos |
| Concrete block | Shifting blocks, drainage | Document height and drainage |
| Natural stone | Settling, frost | Gradual movement isn’t covered |
| Brick | Moisture, cracking | Wear and deterioration aren’t covered |
| Timber | Rot, insects, shorter lifespan | Rot and insects aren’t covered |
| Gabion or boulder | Settling, erosion at the base | Photograph its condition and installation |
How much coverage do you need for a retaining wall?
Your Coverage B limit is one pool for every detached structure on your property. That includes walls, fences, sheds, gazebos, and pools. Here’s how much homeowners insurance you need.
Retaining walls are priced by the square foot of wall face, which is the wall’s length times its height. Here’s what installed walls typically cost, by material.
Cost by material
| Material | Typical installed cost per square foot |
|---|---|
| Timber | $15 to $25 |
| Concrete block | $18 to $30 |
| Segmental block (interlocking blocks with no mortar) | $20 to $35 |
| Poured concrete | $30 to $50 |
| Natural stone or boulder | $25 to $50 |
Walls over 4 feet usually cost about 30% more per square foot, because they need deeper footings and extra steel. They also typically need an engineer ($500 to $2,000) and a permit ($100 to $500). Drainage is a separate cost, usually $300 to $800. Add up your wall, fence, shed, and anything else detached, then compare the total to your Coverage B limit.
What if a retaining wall damages your house or a neighbor’s property?
Two different coverages can come into play.
Damage to your own home: A tree you maintained falls on your wall, and the wall collapses into your neighbor’s yard. If you weren’t negligent, meaning you didn’t ignore a known problem, your neighbor’s own policy usually handles their damage. Coverage B may pay to fix your wall.
Damage to a neighbor, or an injury: If your wall fails and hurts someone or damages their property, personal liability coverage may help, depending on who’s at fault. Retaining wall disputes can involve engineering reports and local rules, so expect an investigation. If the wall is shared or sits on a property line, ownership matters too, so check with us and your local rules.
Here are two examples:
- A tree you maintained falls on your wall, and the wall collapses into your neighbor’s yard. Liability may apply, depending on fault.
- Soil behind a wall you ignored for years gives way and spills into the neighbor’s garage. Coverage is less certain, and neglect can affect the outcome.
This is general information, not legal advice. See personal liability for more.
Do you need to tell your insurer when you build a retaining wall?
For a tall or expensive wall, yes. A big wall can use up your Coverage B limit quickly and leave you underinsured. Taller walls often need permits or engineering, so check your local rules.
A wall on its own usually doesn’t change your price. But an expensive one may mean you need a higher limit, so it’s worth a quick update. When you build or replace one:
- Tell us the materials, height, and length.
- Share the engineering plans and permits, if there are any.
- Recheck your Coverage B limit against the new total.
- Keep receipts and photos of the finished wall.
Should you file a claim for retaining wall damage?
Not always. Ask yourself:
- Is the repair cost clearly higher than your deductible?
- Is the cause clearly a covered event, like a fallen tree, wind, fire, lightning, or a car?
- Have you thought about how a claim could affect your claim history?
- Is the damage urgent, or could it get worse? Waiting can make wall damage pricier.
If the repair costs less than your deductible, a quick fix may beat a claim. Not sure if it’s covered? Ask us first. Learn more about your homeowners deductible.
How to file a retaining wall claim
A damaged retaining wall is stressful. Here’s what to do, step by step.
- Make the area safe and keep people away.
- Document the damage and likely cause with photos, video, and dates.
- Prevent more damage with temporary drainage or support.
- File your claim in the Lemonade App .
- Get a structural or contractor assessment.
- Meet with the adjuster.
How to protect your retaining wall
A little upkeep now can save you a big repair later, so here’s where to start.
- Drainage: Keep weep holes clear, maintain French drains (buried pipes that move water away), and point gutters away from the wall.
- Regular checks: Look for cracks, bulges, leaning, and pooling water.
- Vegetation: Keep large tree roots away, and skip heavy shrubs near the wall.
- Small cracks: Fix them early.
- Tall walls: Get a professional assessment.
- Photos: Keep records of the wall’s condition and construction.
Seasonal checklist:
- Spring: Inspect after frost and clear drains.
- Summer: Trim roots and vegetation.
- Fall: Clear gutters and drains before heavy rain.
- Winter: Watch for ice buildup and signs of frost heave (soil that swells and pushes the wall).
Pro Tip
Photograph your wall every spring. Dated photos make it much easier to show that damage was sudden, not gradual.
Before we go
A damaged retaining wall is a headache, and the coverage rules aren’t always obvious. The short version is that sudden events are usually covered, and slow or ground-related problems usually aren’t.
If your wall is already damaged, make the area safe, take photos, and reach out to us before you start repairs. If it’s fine, now’s a great time to check your limit and photograph it.
Retaining walls FAQs
Does homeowners insurance cover a retaining wall collapse?
It depends on the cause. If a fallen tree, fire, or car brought the wall down, your other structures coverage typically applies. If the cause was earth movement, a landslide, flooding, erosion, poor drainage, or wear and tear, it’s generally not covered.
Does homeowners insurance cover retaining wall damage from heavy rain?
Usually not. Rain alone doesn’t hurt a well-drained wall. Failures after heavy rain typically come from water pressure, shifting soil, or drainage problems, and those aren’t covered. A storm that knocks a tree onto your wall is different, and that may be covered.
Does homeowners insurance cover a retaining wall damaged by a tree?
Usually, yes. A tree that falls on your wall in a storm or high wind is a typical covered event. Coverage may not apply if you ignored a tree you knew was a hazard. Roots slowly pushing blocks out is gradual damage, so that’s typically not covered.
Does homeowners insurance cover retaining wall damage from erosion?
Usually not. Erosion is gradual soil loss, and homeowners policies typically exclude it along with earth movement. A separate flood or earthquake policy generally won’t change that. Good drainage and regular upkeep are your best protection.
Does flood insurance cover retaining walls?
Usually not. The standard NFIP flood policy excludes retaining walls.
NFIP stands for the National Flood Insurance Program, the federal program behind most flood policies. Private flood policies may differ, so read yours closely. Landslides and mudslides may not be covered either, and standard homeowners insurance doesn’t cover flooding at all. Not sure what your policy says? Check the terms before you count on it.
Will a retaining wall raise my homeowners insurance price?
Usually not on its own. A wall doesn’t typically change what you pay, because it falls under your other structures coverage. What can change your price is raising that limit to cover a pricey wall. If you’re planning a big build, tell us the materials, height, and length, and we’ll help you check your limit.
Does homeowners insurance cover a retaining wall shared with a neighbor?
It depends on who owns the wall and what damaged it. A wall that sits on your property line may be partly or fully the neighbor’s, and your policy generally covers only what you own. Sudden damage from an event like a fallen tree may be covered. Check ownership and local rules, then ask us before you file.
Does homeowners insurance cover landscaping and soil behind the retaining wall?
Usually not. The land and soil behind your wall typically aren’t covered, even if a fire or falling tree damages it. Plants and trees may have limited protection, depending on your policy and what caused the damage. Check your policy wording, or ask us before you plan repairs.
How much does it cost to replace a retaining wall?
Installed cost is typically $15 to $50 per square foot of face area. A typical 50-foot wall usually runs $5,000 to $8,000, though tall ones can reach $40,000 or more. Walls over 4 feet add an engineer, a permit, and roughly 30% more per square foot. Get quotes from a few contractors before you decide.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of the policies issued, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage may not be available in all states. Please note that statements about coverages, policy management, claims processes, Giveback, and customer support apply to policies underwritten by Lemonade Insurance Company or Metromile Insurance Company, a Lemonade company, sold by Lemonade Insurance Agency, LLC. The statements do not apply to policies underwritten by other carriers.