Moving to New York City, NY: What Renters Need to Know
The practical realities a renter actually needs to know before settling into New York city.
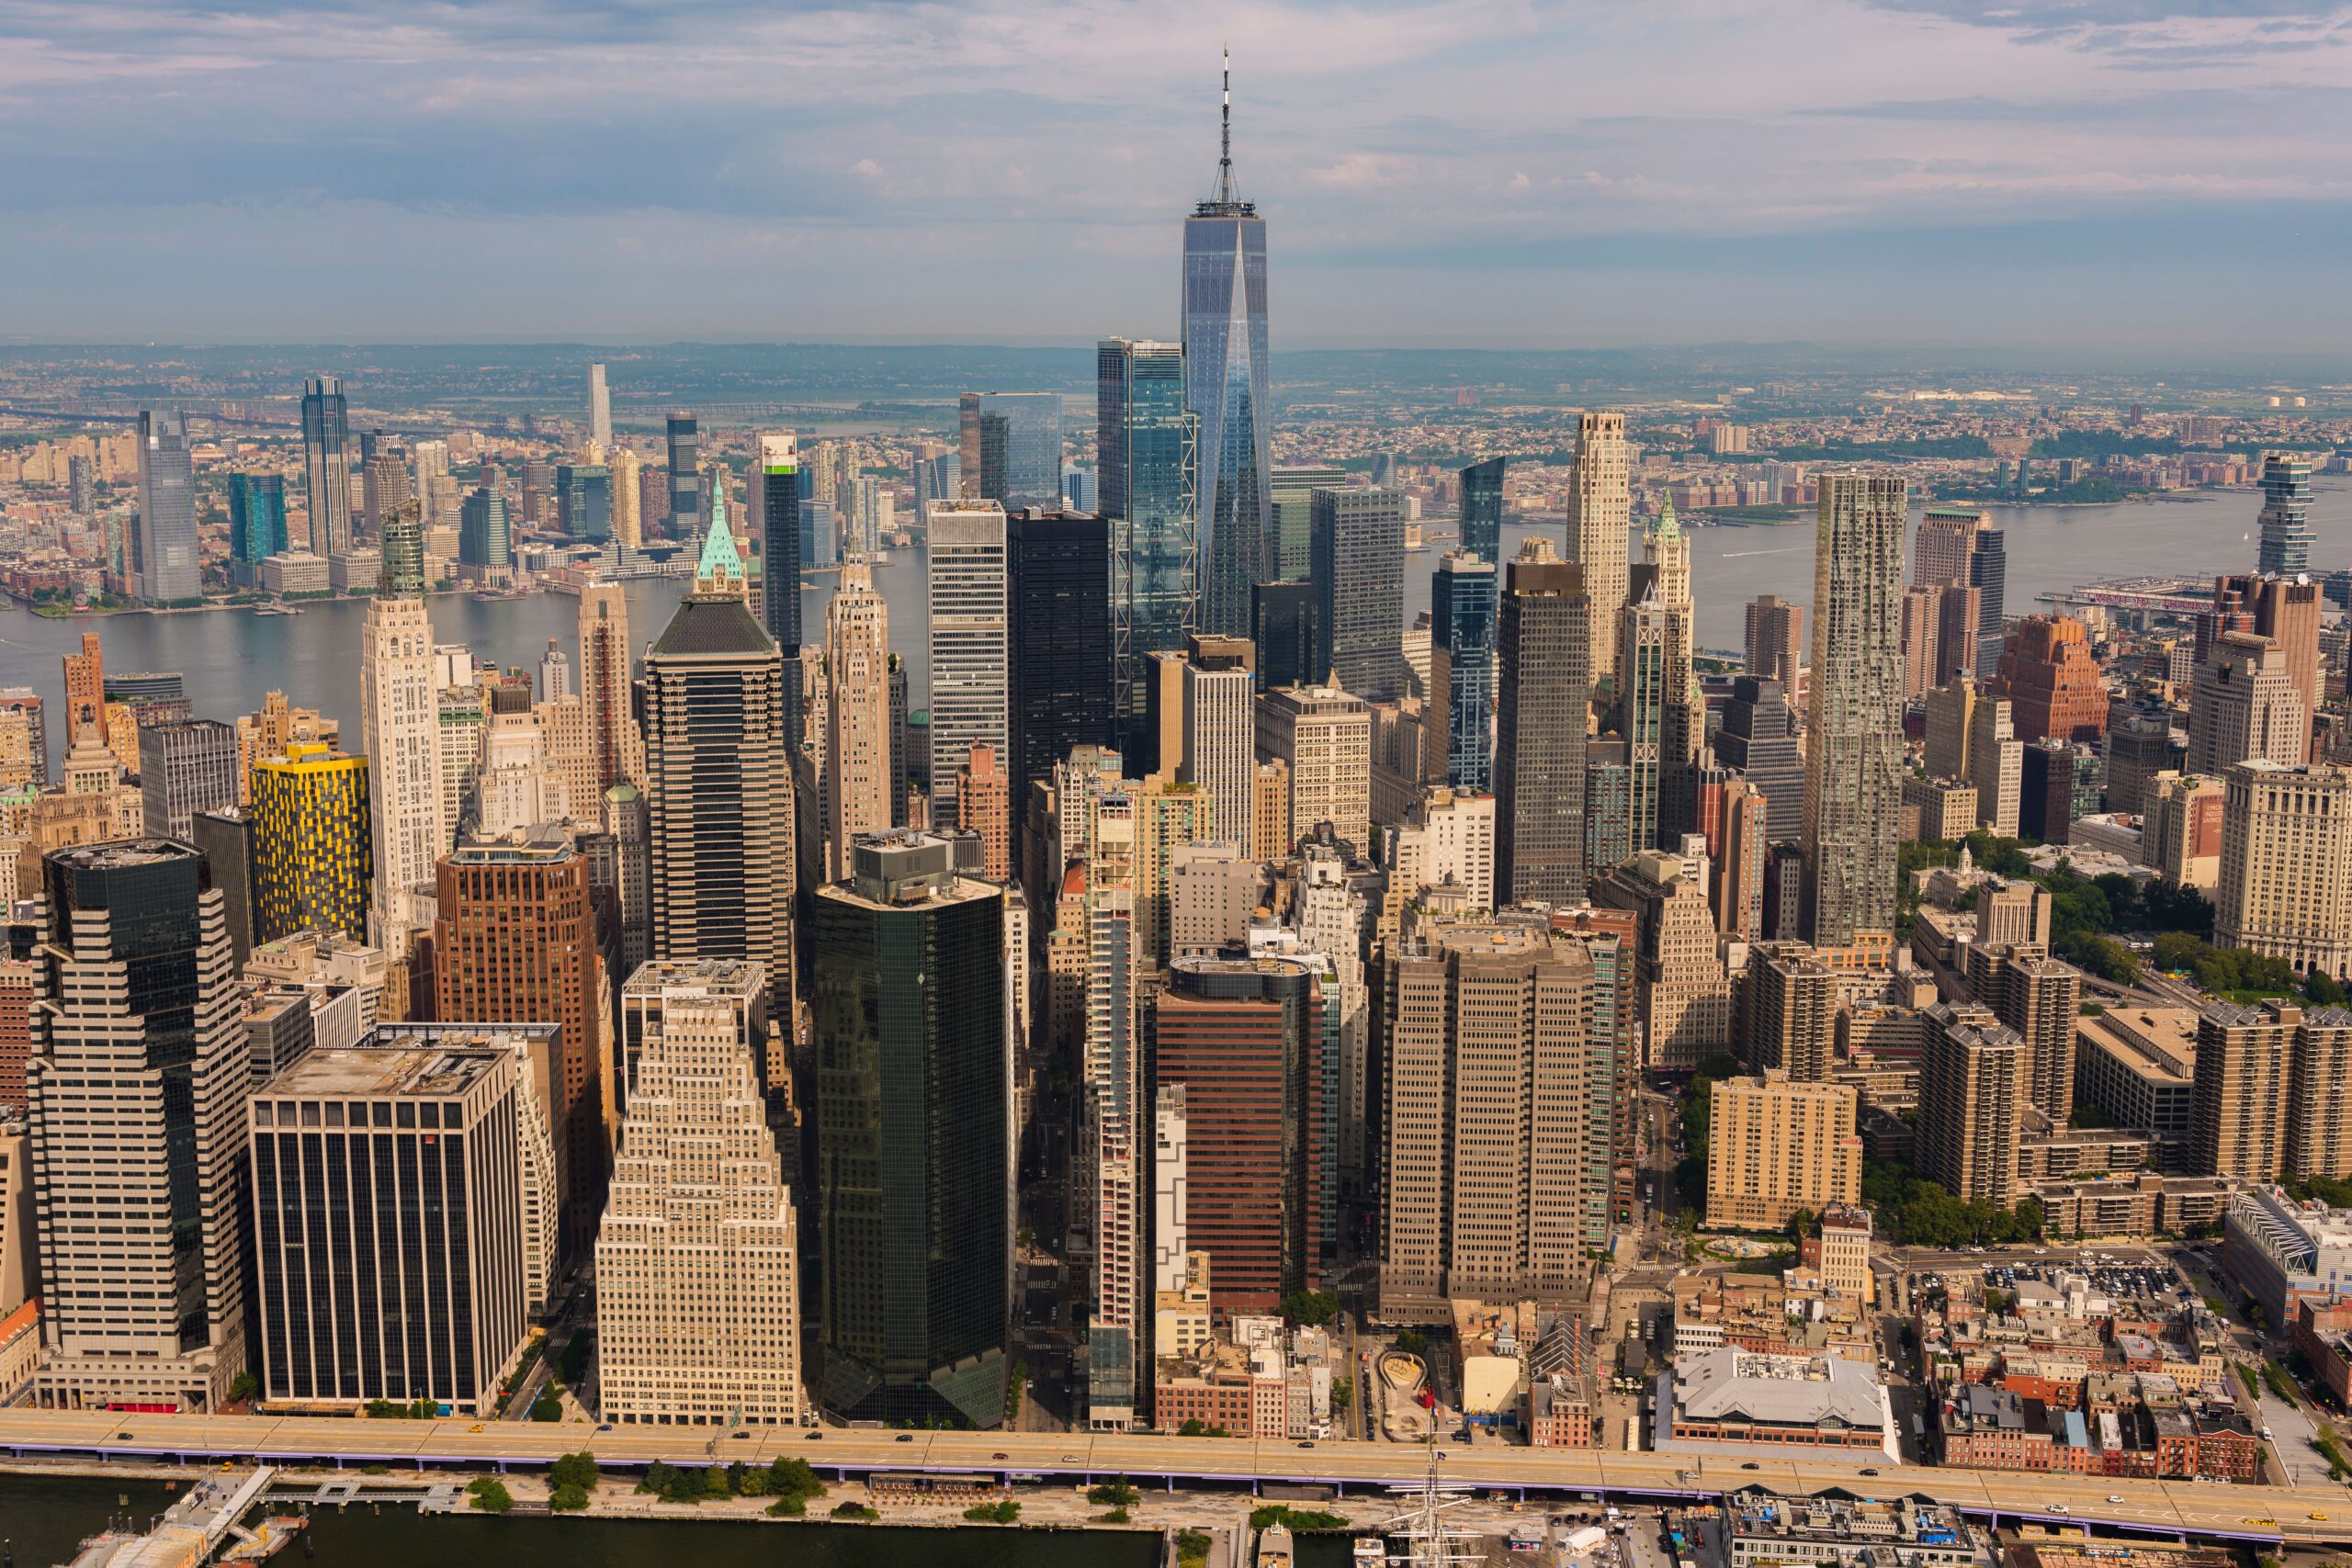
The practical realities a renter actually needs to know before settling into New York city.
You signed the lease, so the hard part’s done. One New York City surprise: you’ll pay a local income tax on top of the state one, so update your budget before your first paycheck lands. Our honest take: get your renters insurance active before the truck pulls up, because your landlord’s policy usually covers the building, not your stuff. Here’s what to sort out next, from deposits and deadlines to daily life.
 TL;DR
Busy, compact, and more neighborly than you’d expect. You’ll walk more, own less, and learn your block quickly.
Our honest take: the first month feels like a lot, and then it clicks. Pick a neighborhood you can see yourself walking around every day, because that matters more than a few extra square feet.
Expect about two months’ rent upfront in New York City (first month plus a one-month deposit), plus a $20 application fee. At a $2,600 one-bedroom, the midpoint of HUD’s citywide range, that’s $5,220 before you get the keys.
Here’s what hits your bank account before move-in:
Lemonade renters insurance in New York City averages around $10 to $15 a month. (Based on Lemonade internal data, 2026.)
The biggest one: if the landlord hired the broker, the landlord pays the broker. Beyond that, your rights depend on whether your apartment is rent-stabilized or market-rate. About 2.4 million New Yorkers live in rent-stabilized apartments, so ask your landlord and look for a rent-stabilization rider in your lease. Many protections got stronger with the Housing Stability and Tenant Protection Act of 2019 (HSTPA).
This isn’t legal advice. If your situation is tricky, a local tenant lawyer or legal aid group is a good next stop.
Film a walkthrough video on move-in day, and email it to your landlord right away. Look closely at radiators, windows, and ceilings, and check for signs of bed bugs and leaks.
| Task | Deadline | Where to do it |
|---|---|---|
| Driver’s license | 30 days after you become a New York resident | DMV office |
| Car insurance | Before you register your car. Out-of-state insurance doesn’t count. | A New York-licensed insurer |
| Car registration | 30 days after you become a New York resident | DMV office, or by mail if you’re still out of state |
| Voter registration | At least 10 days before Election Day (online or in person) | Online, by mail, or at your county board of elections |
Active-duty military often have different rules for registration and taxes. Check with your base first.
NYC has four distinct seasons, and each one has a price tag.
| Hazard / Season | What to expect | What it means for your apartment |
|---|---|---|
| Flash flooding (year-round) | Fast-rising water, plus subway and street flooding | Renters insurance doesn’t cover flooding, so you’ll need a separate flood policy, such as one through the NFIP. |
| Nor’easters and snow (winter) | Heavy snow, wind, and coastal flooding | Ask about heat, and find your water shutoff valve on move-in day. |
| Heat waves (summer) | Long, hot, humid stretches | Ask who pays for the A/C. Window units may need landlord approval. |
| Pests (year-round) | Bed bugs, mice, and roaches | Inspect before you sign, and check the building’s violation history. |
| Building issues | Heat outages, leaks, and broken elevators | Look up the building’s city housing records before you sign. |
Each borough feels like its own city. Here’s a practical breakdown by lifestyle fit.
| Borough | Character & vibe | Best for |
|---|---|---|
| Manhattan | Dense, walkable, and the center of it all | People who want to walk everywhere and be in the middle of the action |
| Brooklyn | Big and varied, with strong neighborhood identities | People who want neighborhood character and a manageable commute to Manhattan |
| Queens | Diverse, with lots of subway access | People who want more space and a straightforward commute |
| The Bronx | Roomy, with space to spread out | People who want more room and are fine checking the commute first |
| Staten Island | Quiet and suburban, with the most car-friendly streets and a free ferry to Manhattan | People who want a slower pace and are fine with a longer commute |
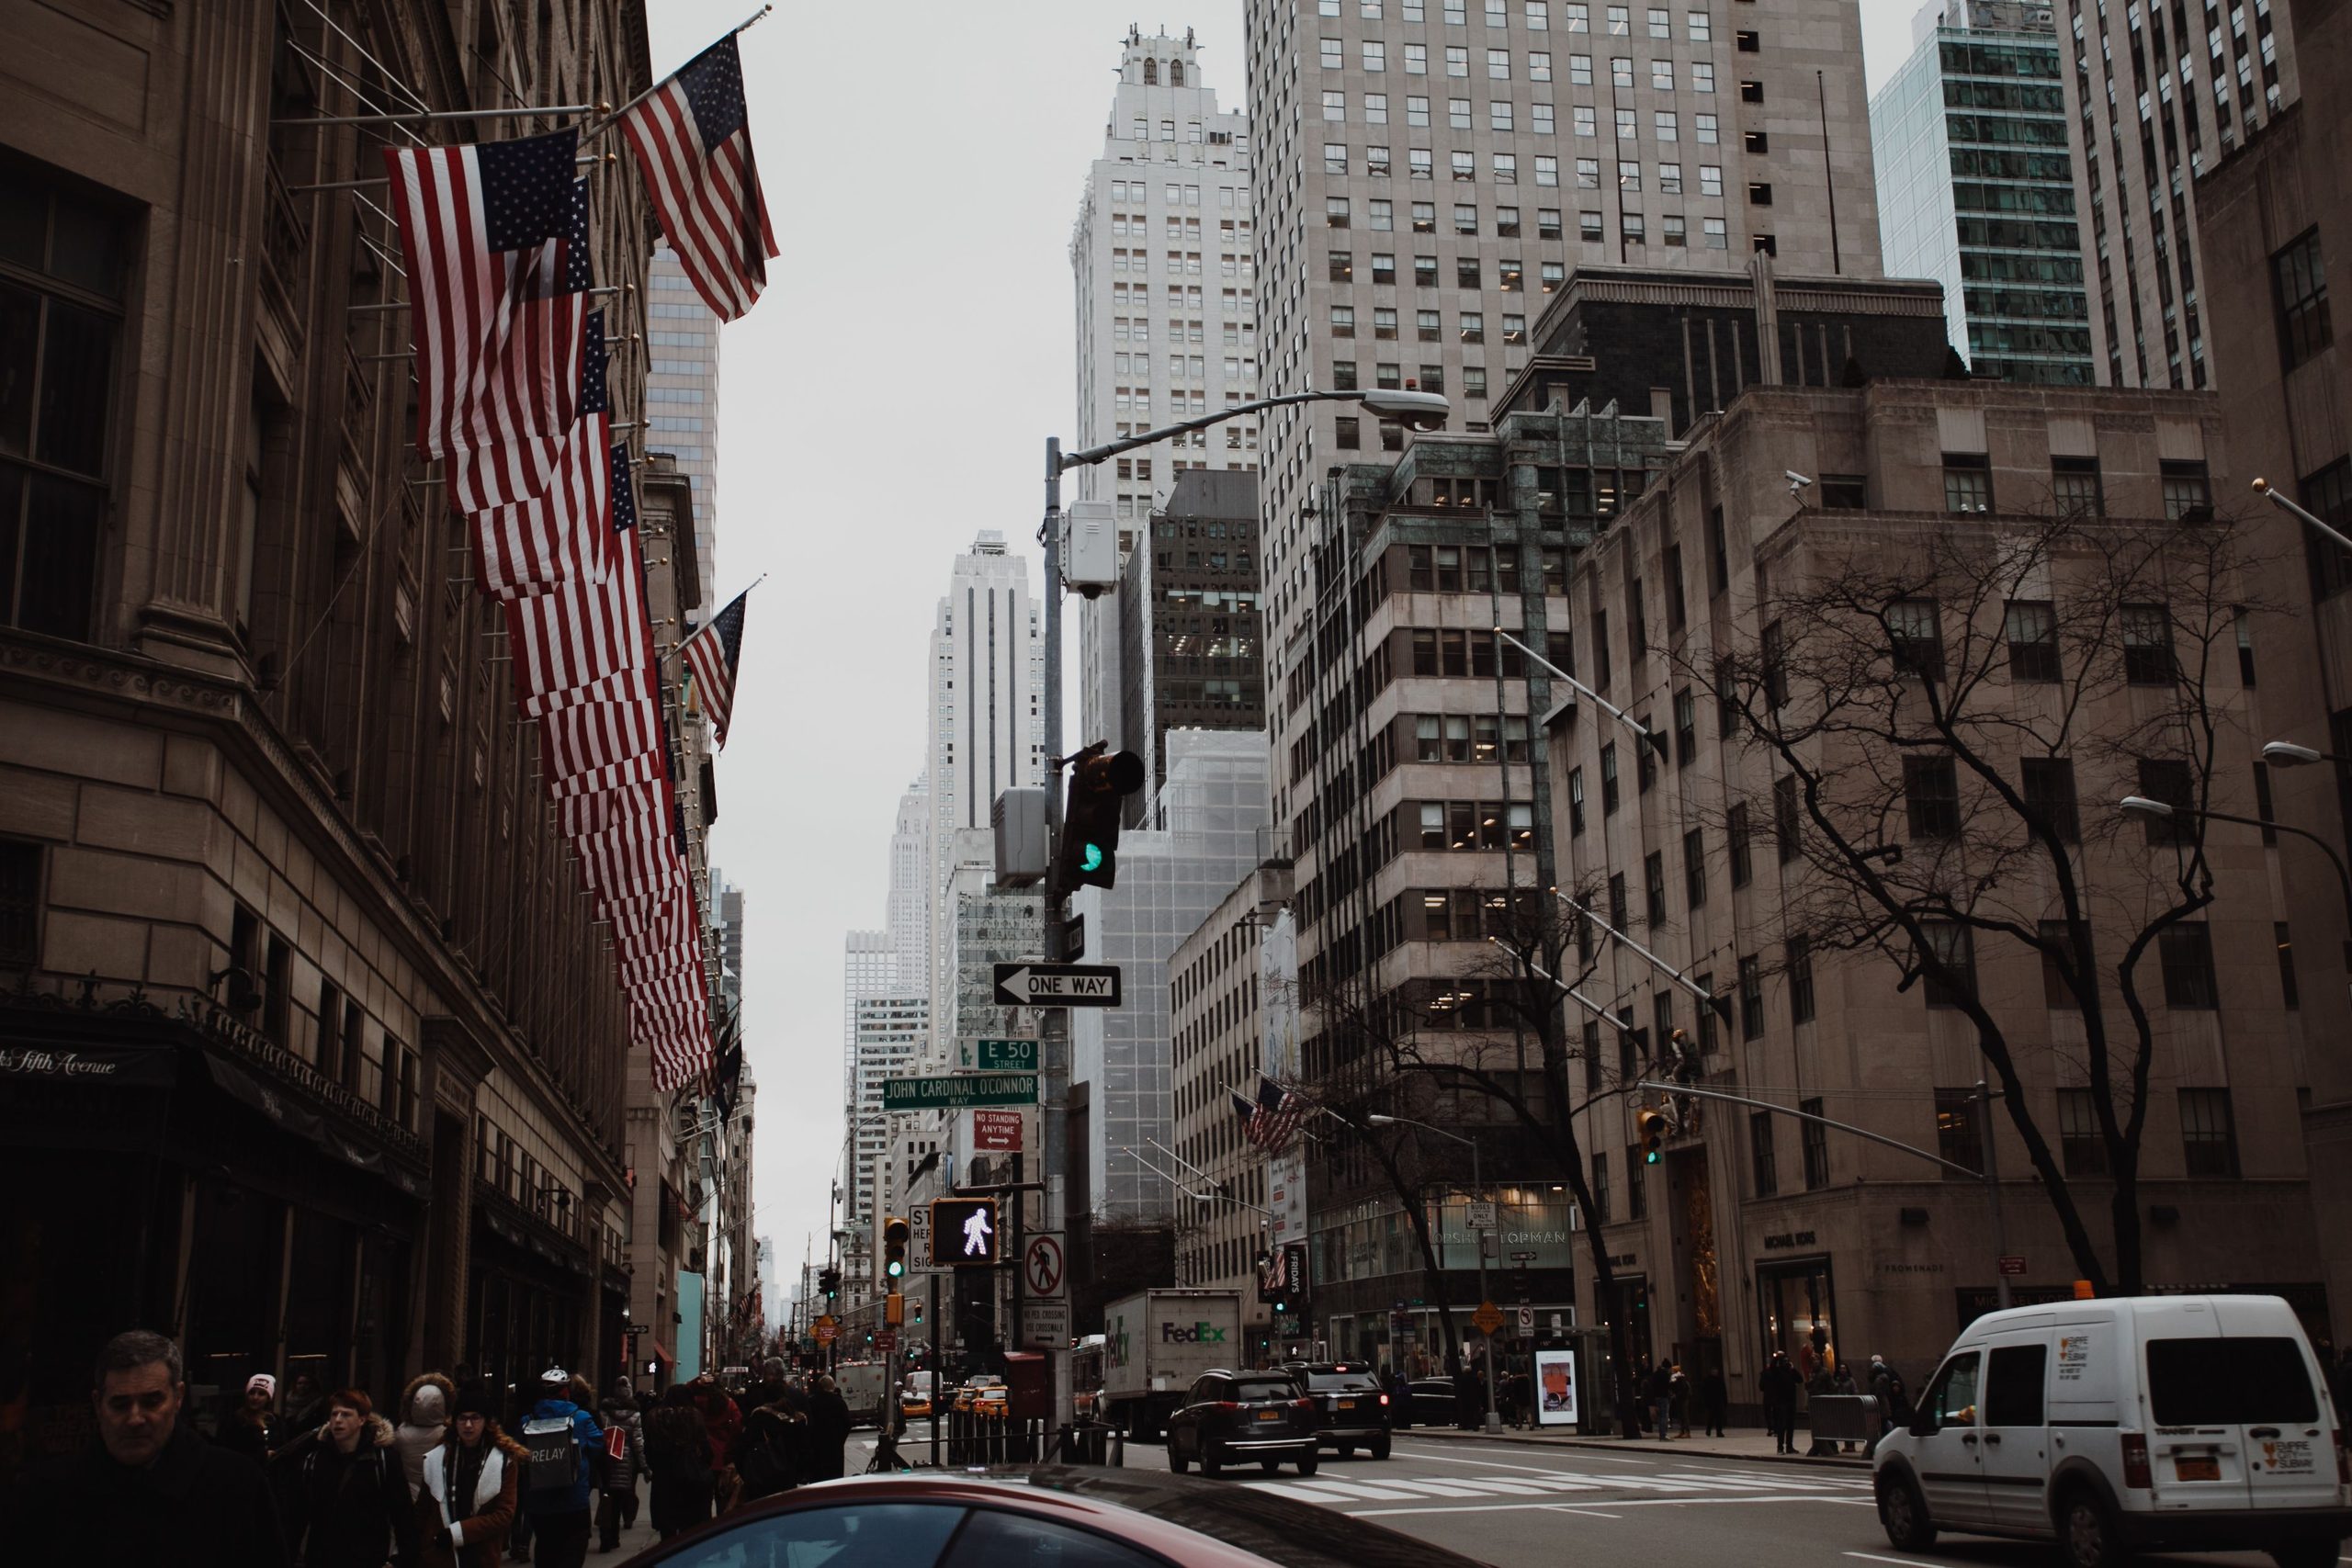
In most of New York City, you can skip the car. Staten Island and parts of eastern Queens are the exceptions. The typical New York City commute runs about 40 minutes each way, per the Census Bureau’s American Community Survey.
| Option | How it works | Reality check |
|---|---|---|
| Subway | Tap to pay with OMNY | Covers nearly every neighborhood and runs all day and night |
| Buses | Same OMNY tap, no cash | Fills the gaps where the subway doesn’t go, especially in Queens, Brooklyn, and Staten Island |
| LIRR and Metro-North | Commuter trains to the suburbs and Manhattan | Handy if you live on the edges of the city or work outside it |
| Ferry | Routes along the waterfront | A scenic option if you live near a dock, but it won’t reach every neighborhood |
| Car | Parking and a congestion toll to plan for | Costs more than most newcomers expect |
Before you sign, test the commute at rush hour. A short distance on a map can mean a long ride.
Your first move in week one: get your power and gas turned on before move-in day, then get your renters insurance active. Here’s who to call.
Your providers depend on your address. Con Edison covers electric in nearly every neighborhood. Gas is where the boroughs split, so check which company serves your building before you book anything.
| Where you live | Electric | Gas | Start service |
|---|---|---|---|
| Manhattan and the Bronx | Con Edison | Con Edison | coned.com or 1-800-752-6633 |
| Brooklyn and Staten Island | Con Edison | National Grid | Con Edison for electric. National Grid at 1-718-643-4050 for gas |
| Queens | Con Edison (PSEG Long Island in the Rockaways) | Con Edison in northern Queens, National Grid in the rest | Both numbers above, depending on your address |
Set up USPS mail forwarding before you move. Then update your employer, bank, IRS, and subscriptions. Already in New York and just switching apartments? Here’s how to change your address on renters insurance.
A renters policy doesn’t follow you across state lines. Moving to New York from another state means canceling your old policy and starting a new one. Start the new policy the day the old one ends, so you don’t go a single night uncovered.
Moving to New York City usually mean a rental truck, a moving company, or a container. Two things can trip you up on moving day: the curb and the building.
Truck parking: For parking purposes, the city treats a moving truck like any other commercial vehicle. A few rules matter most:
Not sure what a block allows? Ask your movers how they handle parking on your street, and read the signs the day before. Here’s the city’s official guide: NYC DOT: Parking a Truck or Commercial Vehicle.
Moving into a New York building often has extra steps. Many buildings require you to reserve the elevator, and some ask for a certificate of insurance from your movers. Book early. Before moving day, run through a moving checklist and check what moving insurance actually covers, and if you’ve never done a long-distance move before, how to pack like a pro will save you a headache or two.
Water damage is the top cause of New York City renters claims, at 29%, with theft close behind at 26%. (Based on Lemonade internal claims data, 2026.)
The most common New York City move-in mistakes come down to money and paperwork. Here’s what to avoid.
New York City rewards preparation. Know whether your apartment is stabilized, ask for every fee in writing, and line up your paperwork before you tour. Then document your move-in condition on day one.
Get your renters insurance active, read your lease carefully (especially the deposit, fee, and renewal terms), and you’ll be ahead of most people who make this move.
Ready to get covered before the moving truck pulls up? Lemonade renters insurance takes as little as 90 seconds to set up.
Usually not. In most of New York City, the subway and buses cover your trips. Staten Island and parts of eastern Queens are the exceptions.
Not if the landlord hired the broker. Under the FARE Act, you only pay a broker you hired yourself. Landlords also have to give you a signed, itemized list of every fee before you sign.
Yes. A deposit can’t be more than one month’s rent, and your landlord has to return it within 14 days after you move out.
Many landlords want yearly income of 40 times the monthly rent. On a $2,600 one-bedroom, that’s $104,000. It’s the landlord’s rule, not state law, so a guarantor may help if you fall short.
State law doesn’t require it, but many landlords and building boards do. It covers your belongings and your liability. Flooding isn’t included. That takes a separate flood policy, such as one through the National Flood Insurance Program (NFIP).
It depends on what you’re after. Manhattan is walkable and central, Brooklyn has neighborhood character, Queens has space and subway access, the Bronx is roomy, and Staten Island is quiet. See the borough table above.
Start with the upfront costs: first month’s rent, a one-month deposit, and a $20 application fee. At $2,600 a month, that’s about $5,220. Then add movers, furniture, and utilities, plus a cushion for your first few weeks.
A few quick words, because we <3 our lawyers: This post is general in nature, and any statement in it doesn’t alter the terms, conditions, exclusions, or limitations of the policies issued, which differ according to your state of residence. You’re encouraged to discuss your specific circumstances with your own professional advisors. The purpose of this post is merely to provide you with info and insights you can use to make such discussions more productive! Naturally, all comments by, or references to, third parties represent their own views, and Lemonade assumes no responsibility for them. Coverage may not be available in all states. Please note that statements about coverages, policy management, claims processes, Giveback, and customer support apply to policies underwritten by Lemonade Insurance Company or Metromile Insurance Company, a Lemonade company, sold by Lemonade Insurance Agency, LLC. The statements do not apply to policies underwritten by other carriers.
Please note: Lemonade articles and other editorial content are meant for educational purposes only, and should not be relied upon instead of professional legal, insurance or financial advice. The content of these educational articles does not alter the terms, conditions, exclusions, or limitations of policies issued by Lemonade, which differ according to your state of residence. While we regularly review previously published content to ensure it is accurate and up-to-date, there may be instances in which legal conditions or policy details have changed since publication. Any hypothetical examples used in Lemonade editorial content are purely expositional. Hypothetical examples do not alter or bind Lemonade to any application of your insurance policy to the particular facts and circumstances of any actual claim.